Al Barsha 1 is one of Dubai’s most commercially active mixed-use communities, a neighbourhood where hundreds of small and medium-sized businesses serve a large and diverse residential population.
For these businesses, restaurants, retail shops, gyms, medical clinics, tutoring centres, and professional service providers, UAE Corporate Tax represents a new and significant compliance obligation that must be navigated correctly to avoid penalties and to take advantage of the reliefs available to eligible businesses.
Professional Corporate Tax Filing Al Barsha 1 support ensures every obligation is met on time and every eligible relief is claimed.
Our corporate tax filing service for Al Barsha 1 businesses provides the accessible, expert guidance that small and medium-sized businesses need to understand their CT obligations, meet every compliance requirement, and, where eligible, take full advantage of Small Business Relief and other available exemptions.
Corporate Tax for Al Barsha 1’s Business Community
Al Barsha 1 businesses face UAE CT obligations that depend on their revenue levels and business structures:
Small businesses (revenues ≤ AED 3 million): Businesses with annual revenues of AED 3 million or less are eligible for Small Business Relief, treating taxable income as nil and effectively paying no corporate tax for the period. However, these businesses must still register with the FTA, file annual CT returns, and make the Small Business Relief election.
Medium businesses (revenues > AED 3 million): Businesses with revenues above the Small Business Relief threshold pay 9% on taxable income above AED 375,000.
For these businesses, correctly calculating taxable income, understanding which expenses are deductible and which are not, is the most important CT compliance task. Accurate bookkeeping is the foundation of this calculation, and ourbookkeeping service keeps records in CT-ready condition throughout the year.
All Al Barsha 1 businesses are required to register with the FTA for CT purposes regardless of whether their income is below the taxable threshold. Failure to register is a compliance violation subject to FTA penalties.
Our Corporate Tax Filing Services for Al Barsha 1
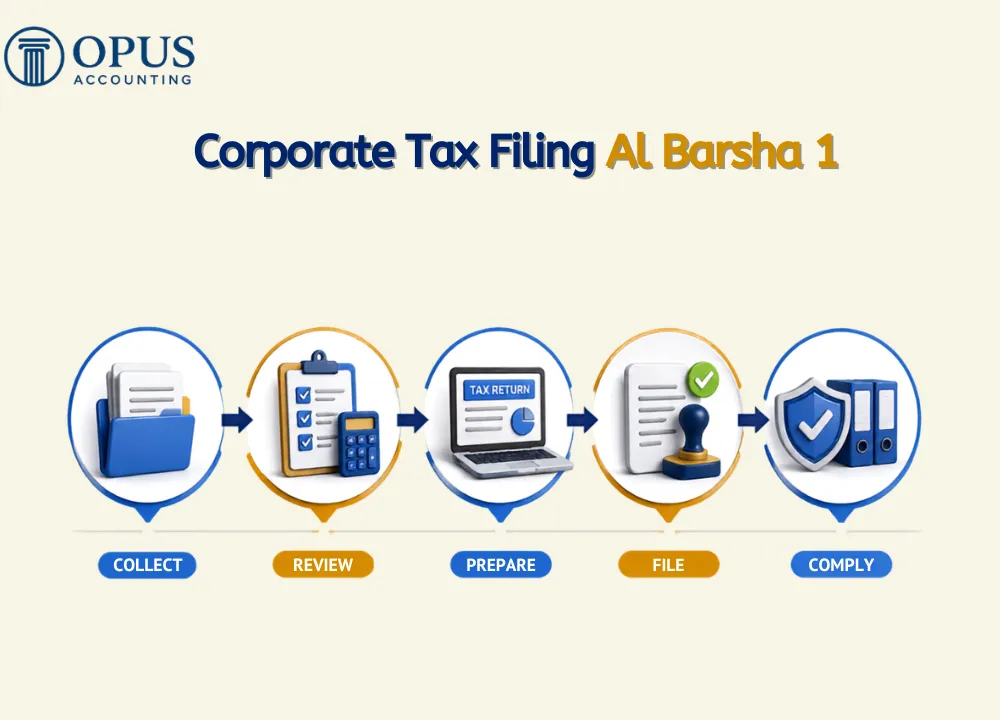
We provide a comprehensive, accessible Corporate Tax Filing Al Barsha 1 service:
FTA corporate tax registration Small Business Relief eligibility assessment and annual election Taxable income calculation from financial records IFRS financial statement preparation where needed Expense deductibility review Related party transaction identification and arm’s length review Annual CT return preparation and FTA submission CT payment scheduling for businesses above the exemption threshold FTA portal management and correspondence CT compliance advisory for business owners Multi-year CT planning
Small Business Relief: What Al Barsha 1 Business Owners Need to Know
Small Business Relief is the most important UAE CT provision for Al Barsha 1’s community businesses, and a thorough Small Business Relief eligibility assessment is where our filing process begins. Understanding it correctly is essential:
Eligibility criteria: The relief is available to resident persons whose revenue for the tax period does not exceed AED 3 million. Revenue is calculated based on the financial records of the business. If revenues in any prior year exceeded AED 3 million, the business may be excluded from future Small Business Relief claims.
Election requirement: Small Business Relief is not automatic. It must be elected in the annual corporate tax return, so businesses that fail to make the election cannot subsequently claim it for that period.
Compliance obligations persist: Electing Small Business Relief does not eliminate compliance obligations. Businesses must still register with the FTA, maintain adequate financial records, and file annual CT returns, as the relief only eliminates the tax payment.
Revenue monitoring: Businesses that are close to the AED 3 million threshold must monitor their revenues carefully. If revenues exceed the threshold in any period, the relief is unavailable for that period. Our Small Business Relief eligibility assessment includes ongoing revenue monitoring so you are never caught out by a threshold breach.
We manage the Small Business Relief assessment and election process as a standard part of our Corporate Tax Filing Al Barsha 1 service for eligible businesses.
Financial Records for UAE CT Compliance
UAE CT requires businesses to calculate taxable income from financial statements prepared in accordance with IFRS (or applicable financial reporting standards for smaller businesses). This creates an important consideration for Al Barsha 1 businesses that have not previously maintained formal IFRS-compliant financial records:
Upgrading record quality: Many small Al Barsha 1 businesses have maintained basic cash-based or summary records rather than IFRS-compliant accounts. An IFRS financial statement upgrade for CT compliance is a prerequisite for accurate corporate tax filing.
Review of existing records: Before preparing the first CT return, we review existing financial records to assess their adequacy for CT purposes, identifying gaps, inconsistencies, or non-IFRS treatments that need to be corrected. This review often runs alongside ourfinancial reporting service to bring statements up to standard.
Bookkeeping and CT integration: For Al Barsha 1 businesses that use our bookkeeping service alongside our CT filing service, the financial records are maintained in CT-ready condition throughout the year, simplifying the CT return preparation process and reducing year-end compliance costs.
Documentation requirements: UAE CT law requires businesses to maintain financial records and supporting documents for seven years. Our document retention policy advisory helps you put appropriate record-keeping practices in place so you always meet this obligation.
Related Party Transactions and Natural Person Businesses
Two areas deserve particular attention for Al Barsha 1 businesses. First, related party transaction identification is essential where a business trades with connected persons or affiliated entities, as these transactions must meet the arm’s length standard under UAE CT law. We review your dealings to flag any related party arrangements and document them correctly.
Second, many Al Barsha 1 operators trade as sole proprietors, which makes natural person business income calculation a distinct compliance task. Where you hold a DED trade licence and conduct business as an individual, your business income is subject to CT and must be calculated separately from personal income, and we advise on exactly how this applies to your situation.
FAQ’s | Corporate Tax Filing Al Barsha 1
1. I run an Al Barsha 1 restaurant with revenues of AED 1.8 million. Do I need to register for corporate tax?
Yes. All businesses subject to UAE CT must register with the FTA, regardless of revenue level or eligibility for Small Business Relief. We manage the registration process and ensure you meet the filing deadline for your first CT return as part of our Corporate Tax Filing Al Barsha 1 service.
2. I am a sole proprietor running a small business. Does UAE CT apply to me?
UAE CT applies to the business activities of natural persons conducting business under a trade licence. If you hold a DED trade licence and operate a business, even as a sole proprietor, you are subject to UAE CT obligations. We handle the natural person business income calculation and advise on the specific provisions applicable to individual businesses.
3. We have never prepared formal financial statements. Can we still file a corporate tax return?
You will need IFRS-compliant financial statements to prepare an accurate CT return. If your records are not currently in this format, we carry out an IFRS financial statement upgrade for CT compliance, review your existing records, make any necessary adjustments, and prepare statements that support the return.
4. How does a Small Business Relief eligibility assessment work?
We review your revenue against the AED 3 million threshold based on your financial records, confirm whether you qualify for the tax period, and make the election in your annual return. Because the relief is not automatic and must be claimed each period, our assessment also monitors revenue so you know well in advance if you are approaching the threshold.
5. What penalties apply if we miss the CT registration deadline?
The FTA imposes penalties for late registration, with the amount depending on the duration of the delay. We recommend registering immediately if you have not done so, and if you are already past the deadline, we manage the registration process and advise on penalty mitigation where possible.
Expert Corporate Tax Filing for Your Al Barsha 1 Business
UAE Corporate Tax is a new reality for every Al Barsha 1 business. Our expert filing service makes that reality manageable, handling every compliance requirement, identifying every available relief, and giving you complete confidence in your CT position. Explore our full corporate tax filing services and the wider range of accounting services we offer across Dubai.
Contact us today for a free consultation, and for Legal Contract Drafting contact Omam Consultancy in Dubai.