Nad Al Sheba 1 is a well-established Dubai community adjacent to Meydan, a neighbourhood with a growing and diverse commercial sector spanning real estate agencies, healthcare practices, hospitality businesses, and professional service firms.
Each of these business types faces distinct corporate tax considerations under the UAE CT framework, from the specific real estate commission income recognition questions facing property businesses to the healthcare practitioner compensation structuring options available to medical and professional service providers.
Ourcorporate tax filing services for Nad Al Sheba 1 businesses provide the specialist expertise needed to navigate these sector-specific CT considerations correctly, delivering accurate taxable income calculations, completeFTA compliance, and effective tax planning for every type of business in this growing community.
[IMAGE HERE: A commercial street view in Nad Al Sheba 1 showing professional offices, healthcare clinics, and retail businesses near Meydan. Alt text: “Corporate tax filing services for Nad Al Sheba 1 businesses near Meydan Dubai”]
Corporate Tax Considerations for Nad Al Sheba 1 Businesses
Different business types in Nad Al Sheba 1 face distinct CT considerations that require specialized corporate tax filing expertise:
Real estate agencies and property management companies: Commission income from property transactions must be recognised correctly under IFRS 15 (Revenue from Contracts with Customers), which determines when commission is earned and therefore taxable. Managing real estate commission income recognition timing is an important CT planning and compliance consideration for property businesses in Nad Al Sheba 1.
Healthcare practices: Medical and dental practices calculate taxable income from clinical revenue after allowable expenses. Healthcare practitioner compensation structuring, whether compensation is structured as employment costs or as drawings from a professional practice, directly affects the taxable income position. Medical equipment depreciation deductibility also plays a significant role in reducing the tax base for practices with substantial capital investment.
Hospitality businesses: Restaurants and event businesses near Meydan recognise revenue from food and beverage sales, event bookings, and catering engagements, with specific hospitality advance booking CT treatment considerations for advance bookings and event deposits that create deferred revenue positions.
Professional service firms: Consulting and advisory businesses recognise revenue from professional engagements under IFRS 15, which may require accrual of income earned but not yet invoiced, affecting taxable income timing. Accurate bookkeeping supports the proper accrual of unbilled revenue for CT purposes.
Our corporate tax filing services for Nad Al Sheba 1 businesses address each of these sector-specific requirements with precision, ensuring every business type files correctly and optimizes its tax position within the legal framework.
Our Corporate Tax Filing Services for Nad Al Sheba 1
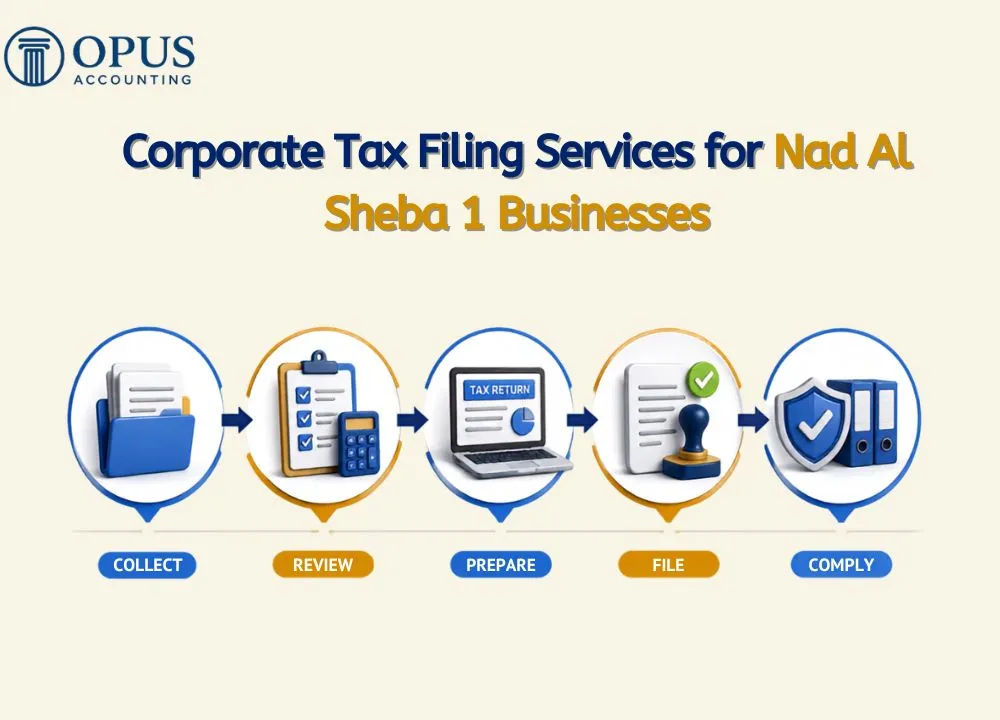
We provide comprehensive corporate tax filing services for Nad Al Sheba 1 businesses covering every aspect of CT compliance and planning:
- FTA Corporate Tax Registration: Complete registration management for new and existing businesses.
- Small Business Relief Eligibility Assessment: Thorough Small Business Relief eligibility assessment for businesses with revenue below AED 3 million, including annual election management in your CT return.
- Taxable Income Calculation with Sector-Specific Revenue Recognition: Applying IFRS 15 principles correctly for each business type, including real estate commission income recognition, hospitality advance booking CT treatment, and professional service accrual accounting.
- Healthcare Practitioner Compensation Structuring Review: Analyzing owner-practitioner compensation structures to optimize the taxable income position for medical and dental practices.
- Medical Equipment Depreciation Deductibility Analysis: Ensuring depreciation policies are IFRS-consistent and correctly applied to maximize allowable deductions for healthcare capital assets.
- Expense Deductibility Review: Comprehensive review of all business expenses to identify and claim every allowable deduction.
- Related Party Transaction Analysis: Identifying and correctly reporting transactions between related entities.
- Annual CT Return Preparation and FTA Submission: Complete preparation, review, and timely submission of your corporate tax return.
- CT Payment Scheduling: Managing payment timelines to avoid late payment penalties.
- FTA Correspondence Support: Handling all FTA queries and correspondence on your behalf.
- Tax Planning for Nad Al Sheba 1 Business Types: Proactive financial planning and CT advisory tailored to your sector.
Real Estate Business Corporate Tax Compliance
Real estate agencies and property management companies in Nad Al Sheba 1 have specific CT considerations that our corporate tax filing services address comprehensively:
Real Estate Commission Income Recognition: Under IFRS 15, real estate agent commission income is recognised when the performance obligation is satisfied, typically at transaction completion. This means commission earned in one period but invoiced or paid in the next must be accrued as income in the correct period for CT purposes. Incorrect real estate commission income recognition can lead to either overpayment or underpayment of tax, both of which create compliance risks.
Property Management Fee Recognition: Recurring property management fees are generally recognised over the service period, monthly or quarterly as the service is delivered. Advance management fees paid by landlords at the start of a management contract must be deferred and recognised over the service period, following the same principles that govern hospitality advance booking CT treatment.
Rolling Transaction Cycles: Real estate businesses with active transaction pipelines may have income recognition timing differences between cash receipts and IFRS accrual accounting. Managing these differences correctly in the CT return requires careful financial statement preparation.
Short-Term Rental Operator Income: For property management businesses managing holiday homes, rental income must be recognised in the period it is earned, which may differ from the period it is collected. Advance bookings paid by guests months in advance create deferred revenue positions that must be managed correctly for accurate CT filing.
Healthcare Practice CT Planning
Medical clinics, dental practices, and healthcare providers in Nad Al Sheba 1 have specific CT planning considerations that make specialized corporate tax filing services essential:
Healthcare Practitioner Compensation Structuring: In a healthcare practice, the compensation paid to practitioner-owners affects the taxable income calculation. Compensation paid as employment income reduces the practice’s taxable income by the amount paid. The structure of owner-practitioner compensation, whether salary versus profit extraction, has CT implications that benefit from advance planning. Our healthcare practitioner compensation structuring review helps practices optimize this balance.
Insurance Receivables Timing: Healthcare practices that bill through insurance schemes recognise revenue when services are delivered, not when payment is received. The timing difference between service delivery and insurance payment collection creates accounting accruals that must be correctly reflected in the CT return. Accurate payroll and staffing records complement this by ensuring practitioner costs are correctly matched against clinical revenue.
Medical Equipment Depreciation Deductibility: Healthcare facilities invest significantly in diagnostic equipment, dental chairs, physiotherapy apparatus, and other medical assets. These assets depreciate over their useful lives, and the annual depreciation charge is a deductible expense that directly reduces taxable income. Medical equipment depreciation deductibility requires IFRS-consistent policies and correct application, which we ensure as part of our corporate tax filing services for Nad Al Sheba 1 businesses.
DHA Compliance Costs: DHA licensing fees, practitioner registration costs, and compliance-related professional fees are generally deductible as business expenses. We ensure these are correctly classified and claimed in your CT return, along with any applicable VAT input recovery.
[IMAGE HERE: A healthcare clinic interior in Nad Al Sheba 1 with medical equipment and a professional reception area. Alt text: “Healthcare practitioner compensation structuring corporate tax filing Nad Al Sheba 1”]
FAQs | Corporate Tax Filing Services for Nad Al Sheba 1 Businesses
1. We are a real estate agency in Nad Al Sheba 1. We complete transactions in different months than when commissions are paid. When is our commission income taxable?
Commission income is taxable in the period in which the performance obligation is satisfied, typically when the property transaction completes. Real estate commission income recognition under IFRS 15 requires accruing the income in the correct period regardless of when cash is received. If commissions are received in a different period, we manage this accrual correctly in your CT return, ensuring your taxable income reflects the economic reality of each transaction.
2. Our Nad Al Sheba 1 medical clinic’s revenues are AED 1.2 million per year. Do we qualify for Small Business Relief?
Yes, revenues of AED 1.2 million are below the AED 3 million threshold. Our Small Business Relief eligibility assessment confirms your full eligibility, and we make the election in your annual CT return, confirming no tax is payable for the period. FTA registration and filing obligations still apply, and our corporate tax filing services for Nad Al Sheba 1 businesses handle both the assessment and the filing process completely.
3. We run a restaurant near Meydan that receives event booking deposits in advance. When is this income taxable?
Advance deposits for future events create deferred income under IFRS. The hospitality advance booking CT treatment means the income is only recognised, and therefore taxable, when the event is delivered and the performance obligation is satisfied. Advance payments received before delivery are not taxable in the period of receipt. We manage this deferred revenue correctly in your CT return.
4. We have both a real estate agency and a property management business. Should these be one company or two for CT purposes?
This is a structure planning question that depends on multiple factors, including the level of related party transactions between the two activities and any group relief considerations. Our corporate tax filing services for Nad Al Sheba 1 businesses include advisory on the CT-optimal structure for businesses with multiple activity streams, considering both compliance efficiency and tax position.
5. How does healthcare practitioner compensation structuring affect our clinic’s CT position?
Healthcare practitioner compensation structuring determines how much of your clinic’s revenue becomes taxable profit versus deductible employment cost. Salary paid to owner-practitioners is a deductible expense that reduces taxable income, while profit distributions are not. The optimal balance depends on your practice’s revenue, cost structure, and the number of practitioners involved. We review this structure as part of our CT planning and recommend adjustments that optimize your tax position while remaining fully compliant.
6. How does Small Business Relief eligibility assessment work for businesses approaching the AED 3 million threshold?
Small Business Relief eligibility assessment requires monitoring your cumulative revenue throughout the tax period. If your Nad Al Sheba 1 business is approaching the AED 3 million threshold, we track your revenue monthly and advise on the implications of crossing it. Once the threshold is exceeded, standard CT rates apply, and your business must maintain audited financial statements. Our proactive monitoring ensures you are prepared for this transition well in advance.
7. What expenses are deductible for professional service firms in Nad Al Sheba 1?
Professional service firms can deduct a wide range of business expenses, including staff salaries and benefits, office rent, professional indemnity insurance, marketing costs, technology and software subscriptions, training and development costs, and client entertainment within FTA-prescribed limits. We conduct a comprehensive expense deductibility review as part of our corporate tax filing services, ensuring every legitimate deduction is claimed and properly documented. Detailed cost tracking supports this analysis.
Expert Corporate Tax Filing for Your Nad Al Sheba 1 Business
Nad Al Sheba 1 businesses are building their presence in a growing and dynamic community. Our expert corporate tax filing services for Nad Al Sheba 1 businesses ensure the CT obligations of your business are managed correctly from the outset, with accurate compliance and effective planning tailored to your specific sector.
Whether you need real estate commission income recognition guidance, healthcare practitioner compensation structuring review, Small Business Relief eligibility assessment, or hospitality advance booking CT treatment expertise, our team delivers the specialized knowledge your Nad Al Sheba 1 business demands.
Contact us today for a free consultation.