Corporate Tax Waiver UAE: If you registered for UAE corporate tax late, the AED 10,000 penalty isn’t necessarily final. A waiver initiative lets eligible businesses avoid it entirely, or get it credited back if already paid — but only within a specific window tied to your own first tax period, not a single fixed date for everyone.
This is one of the more genuinely generous compliance reliefs the FTA has introduced, and it’s still widely under-used simply because businesses don’t realise it exists, or assume the standard 9-month deadline is the only date that matters.
This guide covers exactly who qualifies, how the 7-month window is calculated for your specific business, and what to do next. If you haven’t registered at all yet, see our step-by-step guide to EmaraTax corporate tax registration first.
Quick Answer
The AED 10,000 late registration penalty is waived if your first corporate tax return (or annual declaration) is filed within 7 months of your first tax period ending — instead of the standard 9-month deadline. The waiver is automatic; no separate application is required. If you already paid the penalty and still meet the 7-month condition, it’s credited back to your EmaraTax account automatically.
Why This Waiver Exists
UAE corporate tax was a genuinely new regime for most businesses, effective from financial years starting on or after 1 June 2023. A significant number of taxable persons — particularly SMEs and newly formed companies — missed their registration deadline simply because the requirement, the deadline structure, and the EmaraTax process were all unfamiliar at once.
- The FTA introduced the waiver specifically to avoid penalising a wave of good-faith late registrations during this transition period, rather than treating every late registration as equally deliberate.
- It’s framed as encouraging voluntary, proactive compliance — businesses that come forward and file promptly are treated more favourably than those that continue to delay.
Where the Waiver Came From
The waiver was introduced by the Federal Tax Authority, effective 14 April 2025, applying retroactively from 1 June 2023 — the date UAE corporate tax law first came into force. It sits alongside the AED 10,000 penalty set under Cabinet Decision No. 75 of 2023, rather than replacing it — the penalty still exists, but this specific route lets it be avoided or reversed.
- The FTA’s stated goals: support taxable persons in meeting their obligations, strengthen the UAE’s ease-of-doing-business standing, and encourage voluntary compliance rather than penalising a wave of first-time filers unfamiliar with the new regime
- As of May 2026, the FTA confirmed over 68,600 taxpayers had already benefited, with the number expected to exceed 91,000
- The scale of uptake suggests this genuinely was a widespread issue during the transition into corporate tax, rather than a narrow edge case affecting only a handful of businesses
The 7-Month Rule, Explained
This is the entire mechanism — one condition, calculated from your own first tax period, not a shared calendar date:
| Standard Filing Deadline | Waiver-Qualifying Deadline |
| 9 months after your first tax period ends | 7 months after your first tax period ends |
File your first corporate tax return within that shorter 7-month window, and the AED 10,000 late-registration penalty is waived — even though your standard filing deadline is still 9 months out. Filing between month 7 and month 9 keeps you compliant with the general deadline, but no longer qualifies for this specific waiver.
Worked Examples Across Different Year-Ends
The exact date shifts depending on when your first tax period actually ends — this is the calculation that matters, not a single headline date:
| First Tax Period Ends | Standard Deadline (9 months) | Waiver Deadline (7 months) |
| 31 December 2025 | 30 September 2026 | 31 July 2026 |
| 31 March 2026 | 31 December 2026 | 31 October 2026 |
| 30 June 2026 | 31 March 2027 | 31 January 2027 |
| 30 September 2026 | 30 June 2027 | 30 April 2027 |
Filing by 31 July 2026 waives the AED 10,000 penalty for a business with a 31 December 2025 year-end, even though the standard deadline isn’t until 30 September. This is worth calculating precisely for your own first tax period rather than assuming a single UAE-wide date applies — the 7-month window is different for every financial year-end.
How to Check Your Eligibility in EmaraTax
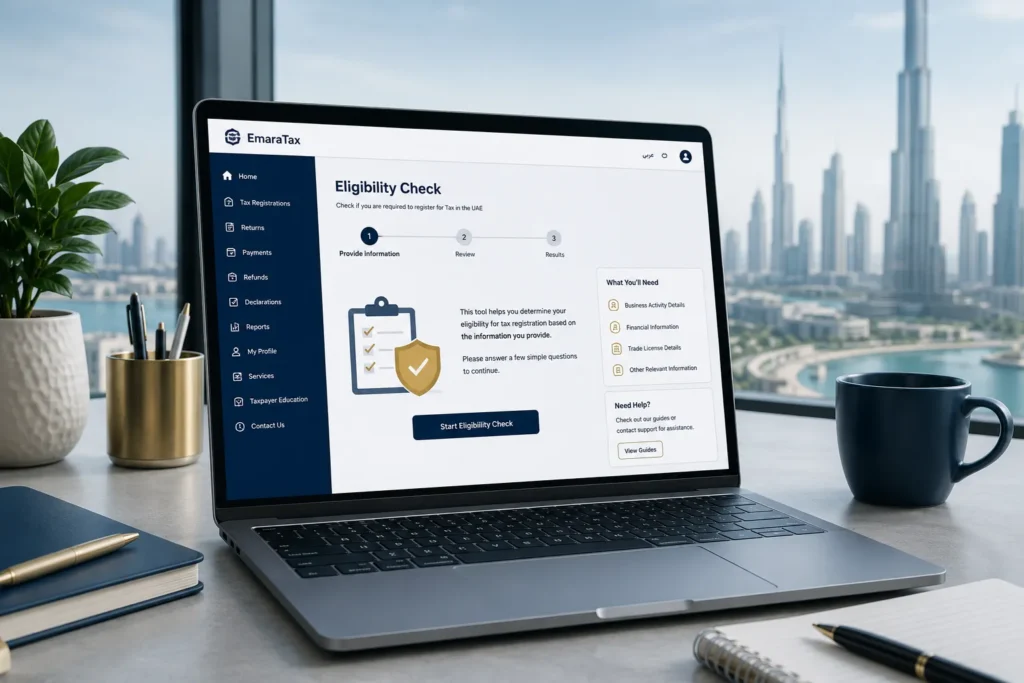
- Log in to your EmaraTax account and confirm your registered first tax period end date under your Taxable Person profile.
- Add 7 months to that date to calculate your personal waiver deadline.
- Check your filing history to confirm whether your first return was already submitted, and if so, on what date.
- If a late-registration penalty appears on your account, check whether it’s been credited back — this typically shows as an adjustment or credit entry rather than a full removal of the original charge.
- If you’re unsure how to read your account status, a registered tax agent can confirm your position directly with the FTA.
Who Qualifies?
The waiver applies broadly across taxable persons and certain exempt persons required to register, including:
- Mainland companies registered late for corporate tax
- Free zone entities subject to corporate tax rules
- Branches of foreign companies operating in the UAE
- Individuals — freelancers and sole establishments — whose turnover crossed the AED 1 million threshold
- Both SMEs and larger enterprises, with no revenue-based exclusion from the waiver itself
The waiver applies specifically to the first tax period only — it isn’t a repeatable relief for late filings in subsequent periods.
There’s no separate eligibility test based on company size, sector, or the reason for the original delay — the 7-month filing condition is the entire test. This is deliberately simple compared to many other tax reliefs that require a business to justify or explain the circumstances of its delay.
It’s Automatic — No Separate Application
This is the part that surprises most businesses, since many other tax reliefs require a formal application, supporting justification, and a waiting period for approval. This waiver works differently:
- Meeting the 7-month filing condition triggers the waiver automatically through EmaraTax — there’s no separate waiver request form to submit
- If the AED 10,000 penalty was already assessed and paid, and the 7-month condition is still met, the amount is credited back to the business’s EmaraTax account automatically, with no separate refund application required
- This applies retroactively too — businesses that filed their first return before the waiver initiative existed, but within what would have qualified as the 7-month window, are also covered
- There’s no waiting period for FTA approval in the way a discretionary relief might require — the system applies the waiver based on the filing date alone
What If the 7-Month Window Has Already Passed?
If you’re past 7 months but still within the standard 9-month deadline, the AED 10,000 late-registration penalty generally stands, but filing before the 9-month mark still avoids late-filing penalties on top of it. This is a materially better position than missing both windows entirely. See our guide on what happens if you miss the UAE corporate tax deadline entirely for the fuller penalty picture.
- A formal reconsideration request can be submitted to the FTA in specific circumstances, but approval is discretionary and not guaranteed — it isn’t a reliable substitute for meeting the 7-month condition
- Filing as soon as possible, even outside the waiver window, still limits further penalty accumulation — waiting doesn’t recover the missed waiver and only adds further late-filing exposure
How This Compares to Other Corporate Tax Relief
The late-registration waiver is one of several relief mechanisms in the UAE corporate tax system, and it’s worth understanding how it differs from the others so you don’t confuse eligibility for one with eligibility for another:
| Relief | What It Covers | How It’s Claimed |
| Late registration waiver | AED 10,000 late-registration penalty, first tax period only | Automatic, based on 7-month filing |
| Small Business Relief | Treats revenue up to AED 3 million as zero taxable income | Actively elected on the return each period |
| Voluntary disclosure | Reduced penalties for self-corrected errors after filing | Submitted proactively through EmaraTax |
These three reliefs address entirely different situations — a business could in principle use all three across different periods, since they aren’t mutually exclusive in the way some other elections are. Understanding which one actually applies to your specific situation avoids wasted effort chasing a relief that isn’t relevant.
What Filing ‘Within 7 Months’ Actually Requires
Qualifying for the waiver isn’t just about submitting something by the deadline — it means filing a complete, accurate first corporate tax return, with all the same standards as any other filing. Our guide to the corporate tax return checklist covers exactly what needs to be ready:
- Finalised financial statements for the first tax period, prepared to the applicable accounting standard
- Any tax adjustment schedules relevant to your business, correctly calculated rather than estimated
- All required non-financial disclosures completed on the return form itself
- The return submitted through EmaraTax, not merely drafted or saved as a work in progress
A rushed, incomplete submission filed just to hit the 7-month mark carries its own risk — an inaccurate first return can trigger a later voluntary disclosure, which brings its own complications even if the AED 10,000 waiver itself was successfully secured. Filing accurately within the window matters as much as filing on time.
Common Misunderstandings About the Waiver
- Assuming 31 July 2026 is a universal deadline for every business — it’s specific to businesses with a first tax period ending 31 December 2025; other year-ends have different 7-month cutoffs, as shown in the table above.
- Assuming the waiver requires a separate application — it doesn’t, and submitting one isn’t necessary or typically actioned differently from simply filing on time.
- Assuming the waiver covers late-filing or late-payment penalties too — it specifically covers the AED 10,000 late-registration penalty only, not other penalty categories that can still apply independently.
- Assuming the waiver applies to every tax period — it’s limited to the first tax period only, and doesn’t carry forward as a standing relief.
- Waiting to file because the standard 9-month deadline still feels comfortable, without realising the waiver window closes two months earlier than that.
- Assuming a credit shown on the EmaraTax account is a mistake or unrelated adjustment, rather than recognising it as the automatic waiver refund taking effect.
Most of these misunderstandings come from treating the waiver as a general amnesty rather than the specific, date-driven mechanism it actually is. The 7-month calculation is the whole test — nothing else about the business’s circumstances changes the outcome.
FAQs | Corporate Tax Waiver UAE
I already paid the AED 10,000 penalty. How do I get it credited back?
If you filed your first return within the 7-month window, the credit is applied to your EmaraTax account automatically — no separate refund request is needed. Check your EmaraTax account balance to confirm the credit has been applied.
Does the waiver apply to my second or third tax period if I’m late again?
No. The waiver is specific to the first tax period only. Late registration or late filing in subsequent periods is subject to the standard penalty framework without this relief.
My first tax period ends 31 March 2026. When’s my waiver deadline?
Seven months after 31 March 2026 is 31 October 2026. File your first return by that date to qualify for the waiver, even though your standard filing deadline would be 31 December 2026.
Do I need to prove I registered late to claim this?
No formal proof submission is required — the waiver is applied automatically based on your filing date relative to your first tax period end, as recorded in EmaraTax.
What if my accountant filed my return but I’m not sure if it landed within 7 months?
Check your EmaraTax account for the exact filing date logged against your first return, and compare it to your first tax period end plus 7 months. If there’s any doubt, a tax adviser can confirm your specific eligibility quickly.
Does this waiver have an overall expiry date for the whole initiative?
The waiver isn’t structured around a single fixed programme end date — eligibility is calculated per business, based on each business’s own first tax period. Businesses whose first tax period ends further in the future will still have their own 7-month window calculated from that date, rather than losing access to the waiver entirely.
Can a tax group benefit from this waiver too?
Yes, in principle — the group’s single consolidated return, filed through the parent entity, is assessed against the same 7-month condition from the group’s first tax period end, in the same way a standalone entity’s return would be.
Does filing a nil return within 7 months still qualify for the waiver?
Yes. The waiver condition is based on filing your first return within the window, not on how much tax is owed. A complete, accurate nil return filed within 7 months qualifies exactly the same way a return with tax due would.
Key Takeaways
- Filing your first corporate tax return within 7 months of your first tax period end waives the AED 10,000 late-registration penalty automatically.
- The window is calculated from your own tax period, not a single UAE-wide date — calculate it precisely rather than assuming a commonly cited example date applies to you.
- No separate application is needed — the waiver, and any refund of an already-paid penalty, both apply automatically once the condition is met.
- The waiver covers only the first tax period and only the late-registration penalty — late-filing and late-payment penalties are separate and unaffected.
- If the 7-month window has passed, filing as soon as possible still limits further penalty exposure, even though the waiver itself is no longer available.
- Over 68,600 businesses had already benefited as of May 2026, with the figure expected to exceed 91,000 — this is a widely used, genuine relief, not a rarely granted exception.
Confirm Your Waiver Eligibility Now
The gap between filing at month 6 and month 8 of your first tax period can be the difference between paying nothing and paying AED 10,000 — worth calculating precisely rather than assuming.
If you’re not certain whether your first return already qualified, or you’re still inside your own 7-month window, this is worth confirming now rather than after the date has passed and the option is gone. A short conversation with a tax adviser now can save far more than the time it takes to have it.
Our corporate tax filing service calculates your exact 7-month deadline, prioritises getting your first return filed within it, and confirms any already-paid penalty is properly credited back. Contact Opus Accounting to check your eligibility today.