Financial reporting services for Academic City businesses form the bedrock of accountability and transparency for entities operating within Dubai International Academic City (DIAC). As the world’s largest purpose-built higher education hub, DIAC is a dynamic free zone community fostering universities, research institutions, training businesses, and knowledge-economy startups.
This unique ecosystem demands a tailored approach to financial management, one that expertly blends standard IFRS requirements with the distinctive operational characteristics of educational and research activities.
From intricate research grant accounting and tuition income deferred recognition across diverse academic calendars to specific reporting mandated by education authorities and research funders, the financial landscape here is truly one-of-a-kind. Opus Accounting provides the comprehensive education sector expertise and IFRS technical knowledge essential for institutions and businesses thriving in this vital knowledge community.
Understanding the Unique Landscape of Financial Reporting in Academic City
Dubai International Academic City stands as a testament to the UAE’s commitment to building a knowledge-based economy. It is not just a collection of campuses; it is an integrated hub where academic rigor meets commercial innovation. This integration creates a unique set of financial reporting challenges and requirements.
Entities here are often multi-faceted, engaging in core educational delivery, pioneering research, vocational training, and the incubation of innovative startups. Generic accounting practices are insufficient to capture the nuances of such operations, making specialized financial reporting services for Academic City businesses absolutely critical.
The free zone status of DIAC also introduces specific regulatory frameworks that interplay with broader UAE financial regulations, including Corporate Tax. Navigating these layers of compliance requires a deep understanding of both local laws and international accounting standards, coupled with sector-specific knowledge. Without this specialized insight, entities risk non-compliance, inefficient resource allocation, and a lack of clear financial visibility, all of which can impede their mission and growth.
Why Specialized Financial Reporting Services for Academic City Businesses are Essential
The complexities inherent in academic and research operations necessitate a highly specialized approach. Here are key reasons why generic accounting falls short in DIAC:
- Blend of IFRS and Sector-Specifics: While IFRS provides the overarching framework, its application must be adapted to education and research contexts. This includes specific interpretations for revenue recognition (e.g., tuition income deferred recognition, research grant accounting), asset management (e.g., research equipment, course content), and expense allocation (e.g., payroll cost allocation across grants and departments).
- Grant Compliance and Accountability: Research institutions heavily rely on grants, each often coming with unique financial reporting stipulations, audit requirements, and performance metrics. Mismanagement can lead to clawbacks, reputational damage, and loss of future funding opportunities.
- Tuition and Student Fee Management: Educational institutions face complex revenue recognition patterns tied to academic calendars, diverse fee structures (local vs. international, undergraduate vs. postgraduate), and student financial aid or bursary programs. Accurate tuition income deferred recognition is fundamental to reliable financial statements.
- Investor and Funder Confidence: Startups and research entities often seek funding from diverse sources, including venture capitalists, government bodies, and philanthropic organizations. Accurate, transparent knowledge startup investor financial statements are paramount for building and maintaining funder trust.
- Regulatory Adherence: DIAC entities must adhere not only to IFRS but also to DIAC authority regulations, accreditation body requirements, and the evolving UAE tax landscape.
Opus Accounting’s expertise ensures that these diverse requirements are met with precision, allowing Academic City businesses to focus on their core mission of education, research, and innovation.
Key Challenges in Financial Reporting Services for Academic City Businesses
The financial operations within DIAC present several nuanced challenges that demand expert handling. Understanding these complexities is the first step towards robust financial reporting services for Academic City businesses.
Revenue Recognition for Diverse Streams
Tuition Income Deferred Recognition: For higher education institutions, tuition fees are typically recognized ratably over the academic term during which educational services are delivered. Fees collected in advance become deferred income, and careful pro-rata tuition income deferred recognition is required, especially when academic terms span across different financial years. This also applies to complex fee structures involving scholarships, discounts, and instalment plans.
Research Grant Accounting Revenue: Research grant accounting requires that grant revenue recognition is often tied to expenditure incurred or the achievement of specific milestones, rather than simple cash receipts. Contract research may involve stage-of-completion accounting (IFRS 15), requiring robust project tracking. Multi-year grants add another layer of complexity, demanding accurate deferrals and accruals.
Commercial Training Fees: Similar to tuition, training course fees are recognized when the service (the course) is delivered. Advance payments for future courses must be meticulously managed as deferred income until the delivery period.
Knowledge Transfer and IP Income: Revenue derived from commercializing research outcomes or licensing intellectual property requires careful assessment under IFRS 15, considering transfer of control, distinct performance obligations, and variable consideration.
Complex Cost Allocation and Tracking
Payroll Cost Allocation Across Grants and Departments: A significant portion of expenditure for educational and research entities is staff salaries. Accurately performing payroll cost allocation across grants and departments for faculty and researchers is crucial. This often necessitates detailed timesheet tracking and robust allocation methodologies. Proper payroll and HR accounting supports this allocation with accurate underlying salary data.
Indirect Cost Recovery: Research grants often include provisions for indirect costs (overheads like utilities, administrative support, infrastructure). Tracking these recoveries and ensuring they are correctly applied and reported within grant budgets is vital for the financial sustainability of research centres. Detailed cost management insights complement this tracking.
Project-Based Expenditure: Managing expenses for numerous, often overlapping, research projects or academic programs requires sophisticated tracking systems to segregate costs, monitor budgets, and report on project profitability or grant utilization.
Fixed Asset Management: Educational and research institutions often have significant investments in specialized equipment, laboratories, and infrastructure. Proper capitalization, depreciation, and impairment testing are essential for accurate financial reporting.
Specific Reporting Requirements
Funder Reporting: Each grant funder may have unique reporting formats, frequencies, and audit requirements. Harmonizing these diverse demands while maintaining consistency with internal accounting records is a significant challenge in research grant accounting.
Accreditation Body Reporting: Higher education institutions must meet specific financial reporting standards set by their accreditation bodies, often requiring supplementary schedules and disclosures beyond standard IFRS.
Knowledge Startup Investor Financial Statements: Knowledge startups, particularly those in pre-profitability phases, require investor-grade knowledge startup investor financial statements that clearly articulate burn rate, cash runway, funding rounds, and going concern assessments.
DIAC Authority Compliance: Adhering to the specific reporting and compliance requirements stipulated by the Dubai International Academic City authority is non-negotiable for all entities operating within the free zone.
Opus Accounting’s Comprehensive Approach to Financial Reporting Services for Academic City Businesses
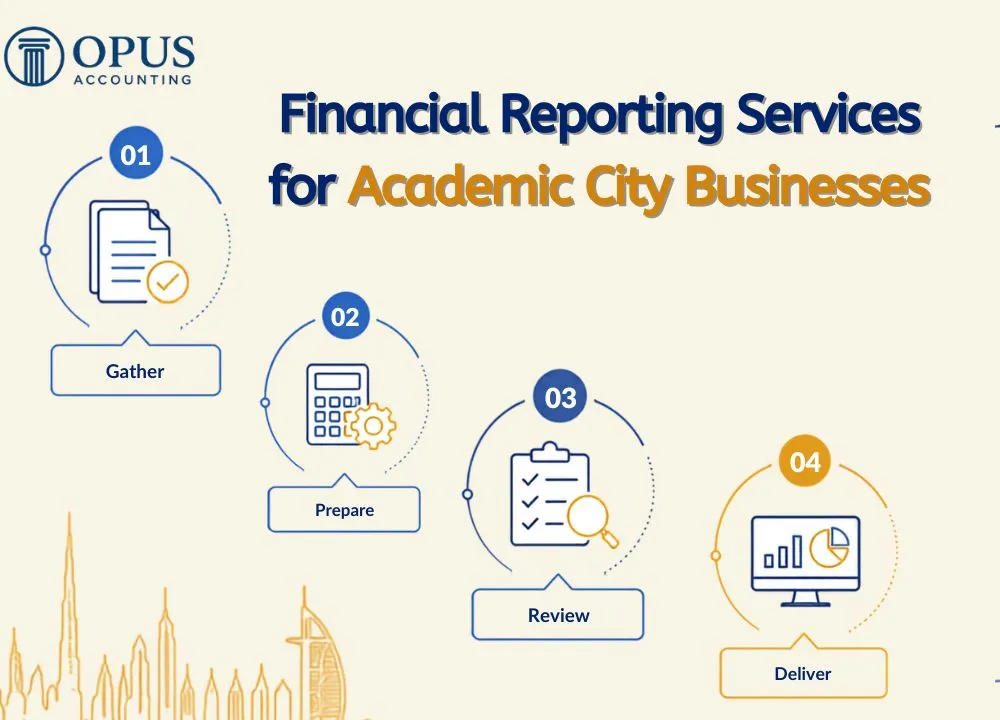
Opus Accounting offers a holistic suite of financial reporting services specifically designed for the unique demands of DIAC entities. Our team combines deep IFRS knowledge with unparalleled sector-specific expertise in education and research, ensuring your financial reporting is accurate, compliant, and insightful.
Financial Reporting for Higher Education Institutions
Universities and higher education institutions in Academic City grapple with complex financial structures. Our services ensure precision:
- Tuition Income Deferred Recognition Schedules: We prepare detailed schedules aligning tuition fee recognition with the academic calendar, correctly managing deferred income for fees collected in advance and accurately recognizing revenue over the period of educational service delivery. This includes managing complex fee structures for domestic vs. international, undergraduate vs. postgraduate, and online vs. residential programs.
- Student Receivables and Bursary Reporting: We implement robust systems for tracking student fee payments, managing instalment plans, and performing aging analysis on student receivables. Our reporting highlights overdue balances and potential collection issues, while also managing the financial impact of scholarships and bursaries. Accurate bookkeeping underpins this receivables tracking.
- Endowment and Restricted Fund Reporting: For institutions with endowments or restricted funds, we establish clear accounting boundaries, ensuring separate reporting of income and expenditure for each fund. This maintains transparency and compliance with donor stipulations.
- Capital Project Accounting: Managing the financial aspects of campus expansion, new facility construction, or significant infrastructure upgrades, including capitalization policies and depreciation schedules.
Research Grant Financial Reporting
Research institutions and grant-funded entities within Academic City demand meticulous financial reporting to track fund utilization and meet funder requirements:
- Research Grant Accounting Framework Establishment: We design and implement tailored accounting systems for each active grant, meticulously tracking budget allocations, expenditure to date, and remaining balances. This provides real-time visibility into grant utilization and forms a core component of our financial reporting services for Academic City businesses.
- Precision Payroll Cost Allocation Across Grants and Departments: As the most scrutinized element of grant financial management, we ensure payroll costs are accurately allocated to grants based on actual time spent on grant-funded activities, supported by robust timesheet records and verifiable methodologies. Our payroll cost allocation across grants and departments methodology ensures every salary charge is defensible under funder audit.
- Indirect Cost Recovery Tracking: We track and ensure correct application and reporting of indirect cost provisions within grant budgets, optimizing recovery for overheads associated with research activities.
- Funder Financial Reports Preparation: We prepare periodic financial reports in the specific format required by each grant funder, ensuring they reconcile seamlessly with your accounting records and accurately represent the grant’s financial progress.
Financial Reporting for Commercial Training Companies
For commercial training providers in Academic City, our services streamline financial processes:
- Course Fee Revenue Recognition: Accurate recognition of course fees as revenue upon course delivery, meticulously managing advance payments as deferred income.
- Instructor Cost Management: Tracking and allocating instructor costs, course material development expenses, and venue hire to individual courses or programs for precise profitability analysis.
- Course Content Asset Management: Accounting for the development costs of proprietary course content, including capitalization and amortisation where appropriate.
- Management Accounts with Education-Specific KPIs: Providing monthly management accounts that include key performance indicators (KPIs) relevant to the training sector, such as course profitability, enrolment rates, and instructor utilization.
Financial Reporting for Knowledge Economy Startups
Pre-profitability startups in DIAC have distinct financial reporting needs, particularly for investors:
- IFRS 15 Service Revenue Recognition: Ensuring compliance with IFRS 15 for service revenue recognition, accurately reflecting the delivery of technology services or intellectual property licensing.
- Technology Development Cost Reporting: Differentiating between research and development expenses, and correctly capitalizing or expensing technology development costs in accordance with IFRS.
- Knowledge Startup Investor Financial Statements: Preparing high-quality quarterly or annual knowledge startup investor financial statements that offer clear visibility into burn rate, cash position, cash runway, and key operational milestones. Expert financial consultancy supports the strategic interpretation of these statements.
- Going Concern Disclosure: Conducting periodic going concern assessments, evaluating the entity’s ability to continue operations, and preparing necessary disclosures, especially for pre-profitability businesses reliant on future funding.
- Funding Round Accounting: Assistance with the accounting for various funding rounds, including equity issuance, convertible notes, and debt financing.
Navigating UAE Corporate Tax QFZP for Free Zone Entities in Academic City
The regulatory environment in the UAE is continuously evolving, with recent significant changes like the introduction of Corporate Tax. For Academic City entities, understanding how UAE Corporate Tax QFZP for free zone entities impacts their financial reporting and compliance obligations is crucial.
- UAE Corporate Tax QFZP for Free Zone Entities: Opus Accounting ensures your financial statements are prepared with UAE CT in mind, providing the necessary breakdowns and classifications to facilitate accurate tax computations and filings. For DIAC entities seeking Qualifying Free Zone Person (QFZP) status, our financial reporting services clearly delineate qualifying and non-qualifying income, maintain substance documentation, and produce the audited financial statements required for QFZP eligibility. Understanding UAE Corporate Tax QFZP for free zone entities is essential for preserving the preferential 0% CT rate on qualifying income, as outlined by the UAE Federal Tax Authority.
- Proactive Compliance: We stay abreast of all updates to IFRS, DIAC regulations, and UAE specific accounting laws, offering proactive advice to ensure continuous compliance and avoid potential penalties. Proper VAT management complements this CT compliance framework.
- Digital Transformation in Accounting: Embracing technology for efficient and accurate financial reporting services for Academic City businesses is paramount. We advise on and implement modern accounting software solutions that streamline data capture, automate routine tasks, and provide real-time financial insights.
FAQs | Financial Reporting Services for Academic City Businesses
1. Our Academic City university collects tuition fees at the start of each term. Our financial year ends in December, but our autumn term runs from September to January. How do we recognise revenue at December year-end?
At December year-end, for the autumn term running from September to January, you would recognize four months of the tuition fee revenue (September to December) within the current financial year. The revenue pertaining to January (one month) must be deferred and recognized in the following financial year. For instance, if the autumn term fee is AED 12,000 per student, we would recognize AED 9,600 (four-fifths) in the calendar year ending December and defer AED 2,400 (one-fifth) to the following year. Our tuition income deferred recognition schedules meticulously maintain this pro-rata split, ensuring the correct amounts are accurately reflected in your year-end financial statements.
2. We are a research centre with three active grants. Each grant has different funder reporting requirements and different year-ends. How do you manage this complexity?
Managing multiple grants with varying requirements is a common challenge in research grant accounting. Opus Accounting treats each grant as a distinct financial reporting stream. We establish a dedicated budget, expenditure register, and balance report for each individual grant. Funder reports are then prepared according to the specific schedule and format required by each respective funder. Furthermore, we coordinate across all active grants to accurately apply payroll cost allocation across grants and departments, indirect cost recoveries, and ensure consistent financial management practices, providing clear visibility of each grant’s financial health.
3. Our Academic City commercial training company offers 3-day public courses at AED 5,000 per participant. Participants often pay in advance. When do we recognise revenue?
Course fees paid in advance are initially recognized as deferred income, as the service (course delivery) has not yet been rendered. Revenue is only recognized when the course is actually delivered. For example, if a participant pays AED 5,000 in December for a course scheduled for January, the AED 5,000 remains deferred income at your December year-end. The full revenue is then recognized in January when the 3-day course is delivered. We manage a detailed course fee deferred income schedule, ensuring revenue is correctly recognized in the period of service delivery, adhering to IFRS 15 principles.
4. Our DIAC knowledge startup is pre-profitability. Our investors want quarterly financial statements. What going concern disclosure do we include?
For pre-profitability startups, going concern assessment is paramount. We prepare a comprehensive going concern assessment each reporting period as part of your knowledge startup investor financial statements. This involves evaluating your cash runway (the number of months of operation funded at the current burn rate), management’s strategic plans for securing continued funding or achieving profitability, and identifying any material uncertainties about the entity’s ability to continue as a going concern. Where such material uncertainty exists, it is clearly and prominently disclosed in the financial statements in accordance with IFRS.
5. How does UAE Corporate Tax QFZP for free zone entities affect Academic City businesses?
UAE Corporate Tax QFZP for free zone entities has significant implications for all DIAC businesses. While free zone entities may qualify for a 0% corporate tax rate on qualifying income, careful assessment and compliance are still required. We help Academic City businesses understand their CT obligations, identify qualifying activities, and ensure their financial reporting systems accurately segregate qualifying and non-qualifying income and expenses. This includes maintaining the audited IFRS-compliant financial statements and substance documentation required for QFZP eligibility, an integral part of our financial reporting services for Academic City businesses.
Expert Financial Reporting Services for Your Academic City Business
Academic City entities are at the forefront of building the UAE’s knowledge economy and shaping its future. The accuracy and integrity of your financial foundations are paramount to this mission. Opus Accounting offers expert financial reporting services for Academic City businesses that ensure these foundations are not only accurately reported but also professionally managed, providing you with peace of mind and the insights needed to thrive.
Contact us today for a free consultation to discuss your specific Academic City financial reporting needs.