Mirdif is one of Dubai’s most established and family-friendly communities, a residential neighbourhood with a thriving commercial sector spanning restaurants, medical clinics, educational centres, retail shops, and professional service firms.
For the businesses in this community, UAE Corporate Tax creates a compliance framework that varies in complexity based on the business type, from straightforward Small Business Relief elections for small community businesses to more nuanced CT analysis for healthcare practices and educational institutions.
Our corporate tax filing services for Mirdif businesses provide the expert, sector-aware guidance that every type of Mirdif business needs, ensuring complete FTA compliance, effective relief claiming, and the CT planning intelligence that helps businesses manage their tax position intelligently. Our team also supports broader needs through dedicated corporate tax filing services across Dubai.
Corporate Tax for Mirdif’s Business Community
Mirdif businesses face UAE CT obligations that reflect the diversity of their commercial activities:
Community retail and food businesses: Most small retail and food businesses in Mirdif have revenues below AED 3 million, making them eligible for Small Business Relief and effectively zero-tax for CT purposes. Compliance obligations still apply regardless of eligibility.
Medical clinics and healthcare practices: Healthcare practices calculate taxable income from clinical revenue after allowable operating expenses. The specific income recognition and practitioner compensation structuring considerations of healthcare businesses make CT planning particularly valuable.
Educational businesses: Nurseries, tutoring centres, and educational providers have specific revenue recognition considerations. Advance fees collected before the education period begins must be treated as deferred income until earned. CT planning for educational businesses benefits from specialist knowledge of educational business deferred revenue treatment.
Professional service firms: Consultancy and advisory businesses in Mirdif calculate taxable income from professional fee revenue after deductible operating expenses, with revenue recognition timing particularly important for project-based engagements.
Our Corporate Tax Filing Services for Mirdif
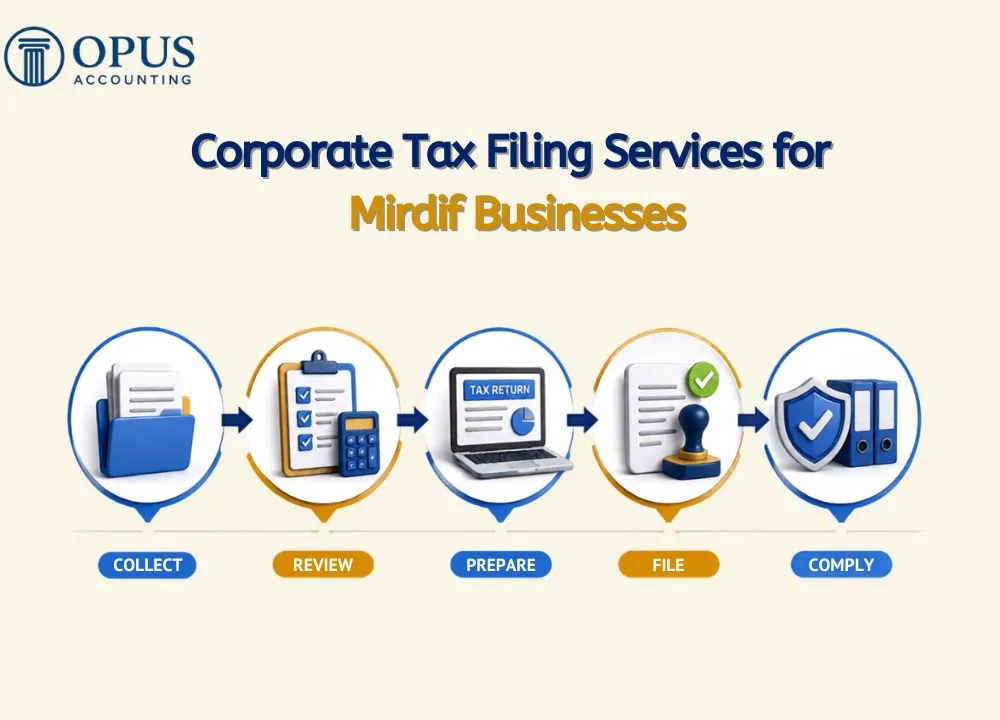
We provide a comprehensive corporate tax filing services for Mirdif businesses, covering:
FTA corporate tax registration for all Mirdif business types Small Business Relief eligibility assessment and election Healthcare practice taxable income calculation Educational business deferred revenue treatment Professional service revenue recognition analysis Expense deductibility review, sector-specific Related party transaction review Annual CT return preparation and FTA portal submission CT payment scheduling and advance payment management FTA correspondence and query handling Multi-year CT planning
Healthcare Practice Corporate Tax
Medical clinics, dental practices, and physiotherapy centres are significant employers and service providers in Mirdif, and they face CT considerations specific to the healthcare business model.
Clinical revenue recognition: Revenue from patient consultations, dental procedures, and physiotherapy sessions is recognised when the service is delivered, which may create timing differences if advance payments or deposits are received before treatment.
Insurance receivables: Healthcare practices billing through insurance companies recognise revenue at the time of treatment delivery, not when insurance payment is received. This distinction in insurance receivables and clinical revenue recognition creates accounts receivable that must be correctly reflected in the financial statements, an area where ourfinancial reporting services provide direct support.
Practitioner compensation: Owner-practitioners who both run the business and deliver clinical services face a specific CT question: how is the practitioner’s compensation treated for CT purposes? Salary paid by the practice is a deductible expense; profit drawn as a dividend is not. Planning the optimal practitioner compensation structuring requires CT expertise.
KHDA and DHA compliance costs: Fees paid for KHDA educational registration, DHA facility and practitioner licensing, and other regulatory compliance activities are generally deductible as business expenses, and correctly tracking these KHDA and DHA compliance costs also supports broadercompliance and licensing obligations.
Educational Business Corporate Tax
Nurseries, tutoring centres, and after-school programmes in Mirdif have specific CT considerations:
Term fee revenue recognition: Tuition fees charged for a term or semester are recognised as revenue over the service period, not when collected. Advance fee payments received before the term begins create deferred income that is only taxable as the education is delivered, a core part of educational business deferred revenue treatment.
Annual enrolment fees: Annual registration or enrolment fees may need to be allocated to the period they cover, not fully recognised as income in the period of collection.
KHDA registration costs: KHDA licensing and registration fees paid by educational businesses are deductible as business expenses, provided they relate to the business’s licensed educational activities.
Teacher and instructor cost deductibility: Salaries and employment costs for teachers and educational staff are deductible as business expenses. Teacher professional development costs, such as external training and qualifications support, may also be deductible.
Capital expenditure on educational facilities: Investment in classroom furniture, educational equipment, and facility fit-out is a capital expenditure deductible through depreciation over the asset’s useful life.
For Mirdif businesses managing payroll alongside these obligations, our payroll and HR accounting services integrate directly with CT-relevant expense tracking.
Get Your Corporate Tax Filing for Mirdif Businesses Right
Whether you run a small retail shop qualifying for Small Business Relief, a medical clinic navigating practitioner compensation structuring, or a nursery managing deferred revenue, Opus Accounting brings sector-aware expertise to every corporate tax filing services for Mirdif businesses we handle.
We ensure accurate FTA registration, correct relief elections, and CT returns that reflect your business’s actual financial position, backed where needed by our audits and assurance capabilities.
Contact Opus Accounting today for a free consultation, and for Legal Contract Drafting contact Omam Consultancy in Dubai.
FAQ’s | Corporate Tax Filing Services for Mirdif Businesses
1. We run a small tutoring centre in Mirdif with revenues of AED 900,000. What do we need to do for UAE CT?
You need to register with the FTA for CT purposes and file an annual CT return. At AED 900,000 revenue, you are well below the Small Business Relief threshold, so we complete the Small Business Relief eligibility assessment and elect the relief in your CT return, meaning no tax is payable. Compliance obligations still apply even at this revenue level.
2. Our Mirdif medical clinic receives advance deposits from patients before treatment. When is this income taxable?
Advance deposits are not taxable until the treatment is delivered. Before delivery, the deposit is a liability in your financial statements. The income becomes taxable in the period when the treatment is performed, and we manage this insurance receivables and clinical revenue recognition correctly in your CT return.
3. We are a Mirdif dental practice with two dentist shareholders. How should their compensation be structured for CT?
Practitioner compensation structuring is a specific CT planning consideration. Salary payments are deductible; profit distributions are not. The optimal structure depends on multiple factors including the practice’s profitability and the practitioners’ other income, and we advise on the most CT-efficient approach for your situation.
4. Do educational businesses receive any specific exemptions from UAE CT?
There is no broad exemption from UAE CT for educational businesses; they are subject to the standard CT framework. Non-profit institutions meeting specific conditions may qualify as qualifying public benefit entities, but for-profit tutoring centres and nurseries follow standard CT rules with educational business deferred revenue treatment applied to advance fees.
5. Are KHDA and DHA fees deductible for CT purposes?
Yes. KHDA and DHA compliance costs, including educational registration, facility licensing, and practitioner licensing fees, are generally deductible as business expenses when they relate to your licensed activities. We track these correctly as part of your annual CT return preparation.