Dubai Silicon Oasis is a government-owned free zone and technology park, a regulatory status that creates specific VAT considerations for companies operating within it. DSO’s designation as a UAE free zone means it is generally outside the UAE VAT system for certain supply types, but the rules governing which supplies are affected are complex, and the distinction between supplies within free zones, between free zones and the mainland, and to or from overseas requires careful VAT analysis.
Professional VAT and indirect tax consulting for Dubai Silicon Oasis companies is essential for navigating this complexity correctly.
Our expert VAT & indirect tax consulting for Dubai Silicon Oasis companies provides the specialist free zone VAT expertise needed to navigate these rules, ensuring every supply is correctly classified, every return is accurately filed, and the Designated Zone VAT treatment of DSO’s unique business environment is managed with authority and precision.
Free Zone VAT: How It Applies to DSO Companies
The UAE VAT treatment of free zone companies is one of the most complex areas of UAE VAT law. Understanding the Designated Zone VAT treatment that applies to DSO is the starting point for every compliance decision. Key principles:
Designated Zones: Certain UAE free zones are designated as “Designated Zones” for UAE VAT purposes, treated as outside the UAE for certain supply types. Dubai Silicon Oasis is a Designated Zone for VAT purposes.
Supplies of goods within a Designated Zone: Supplies of goods between businesses within the same Designated Zone are generally outside the scope of UAE VAT, provided the goods do not enter the UAE mainland. This aspect of Designated Zone VAT treatment is one of the most frequently misunderstood rules, and errors here can triggerFTA penalties.
Supplies of goods from a Designated Zone to the mainland: Supplies of goods from a DSO entity to a UAE mainland recipient are treated as imports into the UAE, subject to import VAT procedures.
Services supplied by DSO entities: Services supplied by DSO entities, including technology services, software, consulting, and professional services, are generally within the UAE VAT scope regardless of the supplier’s free zone location. Technology services place of supply rules determine the VAT treatment, not the physical location of the supplier. Services supplied to overseas recipients may be zero-rated where the place of supply rules result in a non-UAE supply.
Registration requirement: DSO companies that make taxable supplies exceeding the registration threshold must register for UAE VAT. The free zone location does not exempt them from registration. Our VAT and indirect tax consulting for Dubai Silicon Oasis companies includes full registration assessment and management.
Our VAT and Indirect Tax Services for DSO Companies
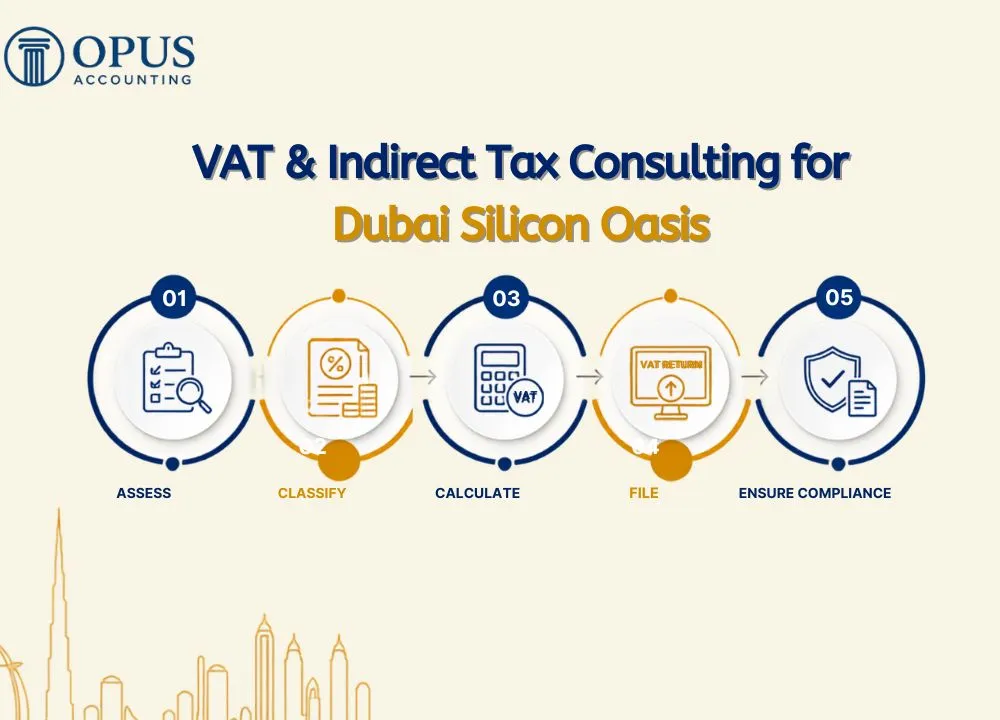
We provide comprehensive VAT and indirect tax consulting for Dubai Silicon Oasis companies covering every obligation:
- Free zone VAT registration assessment and registration management
- Designated Zone VAT treatment analysis for goods and services
- Technology services place of supply determination for B2B and B2C scenarios
- Zero-rated services to overseas clients, including conditions and evidence requirements
- B2B and B2C VAT treatment for technology and SaaS businesses
- Reverse charge mechanism for overseas service purchases
- VAT return preparation and FTA portal submission
- Input tax recovery review with technology business-specific considerations
- Inter-entity supply VAT treatment for DSO group structures
- FTA audit support and voluntary disclosure management
- VAT advisory for new DSO business activities
This end-to-end service means your VAT and indirect tax consulting for Dubai Silicon Oasis is handled with the precision that free zone compliance demands. For businesses that also need their underlying financial records in order, our DSO bookkeeping support ensures your VAT data is always accurate at source.
VAT on Technology Services from DSO
Technology companies in Dubai Silicon Oasis supply services, including software development, IT consulting, SaaS platforms, and digital marketing, that have specific UAE VAT treatment. Understanding technology services place of supply is critical for every DSO tech business.
Place of supply for services: UAE VAT legislation applies place of supply rules to determine whether a service is within the UAE VAT scope. For B2B services (supplied to VAT-registered businesses), the place of supply is generally where the recipient is established. For B2C services (supplied to individuals), special rules apply, particularly for electronically supplied services. Correctly applying technology services place of supply rules is one of the most common areas where DSO businesses make avoidable errors.
Services to UAE mainland clients: Technology services supplied to UAE mainland businesses are subject to UAE VAT at 5%. The DSO supplier charges 5% VAT on its services to mainland clients, just as a mainland supplier would. The Designated Zone VAT treatment does not change this for services.
Services to overseas clients (B2B): Technology services supplied to businesses established and carrying on business outside the UAE are generally zero-rated, meaning the place of supply is outside the UAE. Zero-rated services to overseas clients require documentary evidence of the overseas business status of the recipient. Without proper evidence, the supply defaults to standard-rated, and you owe 5% VAT. Our VAT and indirect tax consulting for Dubai Silicon Oasis companies ensures the correct documentation is in place for every zero-rated overseas supply.
Electronic services to overseas consumers: Electronically supplied services to overseas non-business consumers require specific place of supply analysis. Where the consumer is outside the UAE, the supply may be outside the UAE VAT scope entirely.
SaaS and Subscription Service VAT
SaaS businesses in Dubai Silicon Oasis supply software access on a subscription basis, creating specific VAT timing and categorisation considerations. Getting SaaS subscription VAT right requires attention to several technical rules.
Continuous supply VAT timing: SaaS subscriptions are continuous supplies. VAT is charged as the supply is made, and each billing period generates a taxable supply and a VAT invoice requirement. Advance payments for multi-month or annual subscriptions create a tax point at the time of payment or invoice, whichever is earlier. SaaS subscription VAT timing is particularly important for annual plans, where the full VAT obligation arises upfront.
Electronic services classification: SaaS and digital services are classified as “electronic services” under UAE VAT, with specific rules governing their VAT treatment when supplied to non-business consumers. This classification determines whether the service falls under general place of supply rules or the specific electronic services provisions.
Enterprise client versus consumer: B2B subscription revenue (to business clients with valid UAE VAT registration numbers) is treated differently from consumer subscription revenue for VAT purposes. We manage the SaaS subscription VAT treatment for each client category correctly, ensuring your returns reflect the right classification.
Foreign currency invoicing: DSO SaaS companies often invoice in USD or other foreign currencies. UAE VAT must be reported in AED, requiring currency conversion at the exchange rate applicable at the tax point. Errors in currency conversion directly affect your VAT return accuracy. Our VAT and indirect tax consulting for Dubai Silicon Oasis companies handles these conversions correctly every period.
Reverse charge on overseas inputs: Many DSO SaaS businesses purchase cloud hosting, development tools, or third-party APIs from overseas providers. These purchases trigger the reverse charge mechanism, which requires you to account for VAT as if you made the supply yourself. For fully taxable businesses, the net VAT cost is typically zero (output VAT is recorded and recovered as input VAT in the same return), but the obligation to account for it correctly remains, and failure to do so is a compliance breach.
FAQ’s | VAT & Indirect Tax Consulting for Dubai Silicon Oasis
1. We are a DSO technology company. Our clients include both UAE mainland businesses and overseas companies. How does VAT work for each?
Services to UAE mainland businesses are subject to 5% VAT, which you charge and include in your VAT return as output tax. Services to overseas businesses (with the recipient established outside the UAE and using the services in the course of their business outside the UAE) may qualify as zero-rated services to overseas clients, subject to maintaining the required evidence. We assess each client relationship and advise on the correct VAT treatment as part of our VAT and indirect tax consulting for Dubai Silicon Oasis companies.
2. We use cloud hosting from an overseas provider. Do we pay VAT on this?
Yes. Services received from an overseas provider are subject to the reverse charge mechanism. You account for VAT as if you made the supply yourself, recording output VAT and (where input tax recovery conditions are met) recovering the same amount as input tax in the same return. The net VAT cost is typically zero for fully taxable businesses, but the reverse charge mechanism entries must appear correctly on your VAT return regardless.
3. Our DSO company sells annual SaaS subscriptions. When does the VAT obligation arise for an annual payment?
For a payment in advance, the tax point is the earlier of the date of payment or the date of invoice. If you invoice and receive payment at the start of the annual subscription, the full annual subscription fee (inclusive of VAT) creates a VAT obligation at that point, not spread over the subscription year. SaaS subscription VAT timing catches many businesses off guard, especially those with significant annual billing.
4. As a DSO free zone entity, are we automatically exempt from UAE VAT?
No. Free zone location does not create VAT exemption. DSO companies that make taxable supplies above the registration threshold must register for UAE VAT and comply with all VAT obligations in the same way as mainland businesses. The Designated Zone VAT treatment affects certain goods transactions but does not exempt services from VAT.
5. Can Opus Accounting also handle our corporate tax filing alongside VAT?
Yes. We provide VAT and indirect tax consulting for Dubai Silicon Oasis companies alongside corporate tax filing support. Managing both together ensures consistency between your VAT returns and CT return, prevents conflicting revenue recognition positions, and gives you a single point of contact for all tax compliance matters.
Expert VAT Consulting for Your DSO Company
Dubai Silicon Oasis technology companies operate in a complex VAT environment that rewards specialist knowledge. From Designated Zone VAT treatment and technology services place of supply to SaaS subscription VAT, the reverse charge mechanism, and zero-rated services to overseas clients, every element of DSO VAT compliance demands precision. Our expert VAT and indirect tax consulting for Dubai Silicon Oasis ensures your compliance is as sophisticated as the technology your business builds.
Contact Opus Accounting today for a free VAT consultation and discover how specialist free zone VAT expertise can protect your DSO business.