Jebel Ali Free Zone (JAFZA) is one of the world’s largest and most established free zones, a global trade and logistics hub home to thousands of trading companies, manufacturers, distributors, and multinational regional operations.
For JAFZA companies, VAT carries a distinct layer of complexity that mainland businesses do not face, because much of JAFZA operates as a VAT Designated Zone, a status with its own specific VAT treatment for goods, alongside the reverse charge, free zone to mainland supplies, and the import, export, and re-export flows that define international trade. Expert VAT & Indirect Tax Consulting for JAFZA Companies ensures every one of these is handled correctly.
Our VAT and indirect tax consulting service for JAFZA companies provides the designated-zone-aware, trade-aware expertise that the free zone’s traders, manufacturers, and distributors need, ensuring every supply is correctly classified under the Designated Zone rules, every legitimate input is recovered, and every FTA obligation is met accurately and on time.
VAT for JAFZA Companies
JAFZA companies encounter UAE VAT under a framework shaped by the zone’s Designated Zone status and its international trade character, each element with its own treatment.
Designated Zone status: Much of JAFZA is a VAT Designated Zone, meaning certain supplies of goods within and between designated zones are treated as outside the scope of UAE VAT, subject to specific conditions, which fundamentally affects how goods transactions are treated.
Free zone to mainland supplies: Supplies from a JAFZA company to a mainland UAE customer are treated as imports into the mainland, with specific VAT consequences that must be handled correctly.
Complex supply chains: Many JAFZA businesses operate multi-party, cross-border supply chains where goods move between zones, countries, and the mainland, each movement carrying its own VAT treatment.
Import, export, and re-export: JAFZA’s trade businesses handle substantial import, export, and re-export activity, each with distinct VAT treatment.
Our VAT and Indirect Tax Services for JAFZA Companies
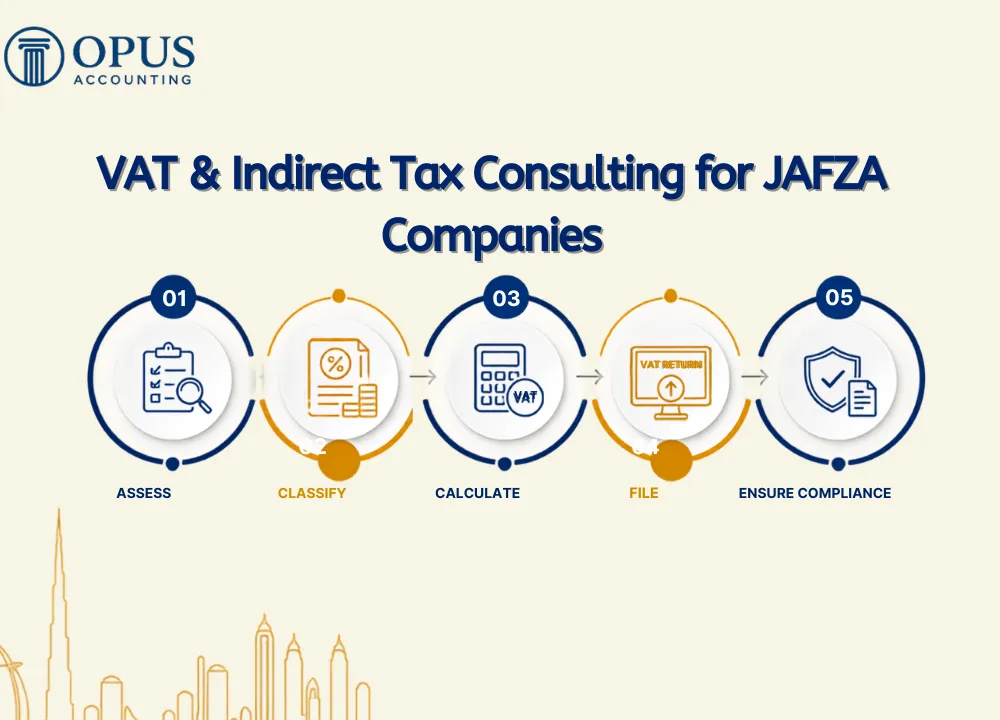
We provide a comprehensive VAT & Indirect Tax Consulting for JAFZA Companies service:
- Designated Zone VAT framework analysis and application.
- Free zone to mainland supply VAT treatment.
- Complex supply chain VAT structuring and compliance.
- Reverse charge mechanism accounting.
- Import, export, and re-export VAT treatment.
- Input tax recovery review and optimisation.
- VAT registration, deregistration, and compliance management.
- Quarterly VAT return preparation and FTA portal submission.
- FTA voluntary disclosure and audit support.
- VAT health checks and compliance reviews.
The Designated Zone Framework and Mainland Supplies
The single most important VAT consideration for JAFZA companies is the Designated Zone framework, and how supplies are treated within it and when goods leave it for the mainland.
Designated Zone VAT framework: Much of JAFZA holds VAT Designated Zone status, under which certain supplies of goods within a designated zone, or between designated zones, are treated as outside the scope of UAE VAT, provided specific conditions are met around the movement and use of the goods. However, this treatment applies to goods and not generally to services, which follow the normal VAT rules, and the conditions are precise, misapplying the Designated Zone treatment is a common and costly error. Designated Zone VAT framework analysis ensures your goods transactions are correctly assessed against the designated zone conditions, so the right treatment is applied to each and your VAT position is accurate and defensible.
Free zone to mainland supply VAT: When a JAFZA company supplies goods to a mainland UAE customer, the transaction is generally treated as an import into the mainland, and the VAT consequences, including who accounts for the import VAT, must be handled correctly. Free zone to mainland supply VAT ensures these transactions are treated properly, with the import VAT position correctly established, so both the JAFZA supplier and the mainland customer meet their obligations and the supply chain remains compliant.
Services versus goods: Because the Designated Zone treatment applies to goods rather than services, JAFZA companies supplying services must apply the normal VAT rules, and we ensure the distinction is drawn correctly so services are not mistakenly treated as out of scope.
Supply Chains, Reverse Charge, and Trade VAT
Beyond the Designated Zone framework, JAFZA’s international trade businesses face VAT across complex supply chains, overseas purchases, and their import, export, and re-export activity.
Complex supply chain VAT: Many JAFZA companies operate multi-party, cross-border supply chains, where goods may move from an overseas supplier, through the designated zone, and on to a mainland or export customer, with several parties and jurisdictions involved. Complex supply chain VAT analyses each movement in the chain and applies the correct VAT treatment to each, so a transaction involving several steps and parties is handled correctly at every stage, avoiding the errors that complex chains so easily produce and keeping the whole chain compliant and efficient.
Reverse charge mechanism: When a JAFZA company buys services from an overseas supplier, the reverse charge mechanism applies, the company accounts for both the output and input VAT on the imported service in the same return. Reverse charge mechanism accounting is usually VAT-neutral for a fully taxable business, but it must be recorded correctly, and failing to apply the reverse charge is a common error we help businesses correct.
Import export and re-export VAT: JAFZA’s trade businesses handle substantial import, export, and re-export activity, each with its own VAT treatment, import VAT on goods entering the mainland, zero-rating on exports where conditions are met, and specific treatment for re-exported goods that pass through without entering the mainland market. Import export and re-export VAT ensures each of these flows is treated correctly and documented properly, so your trade VAT is accurate and your zero-rating and out-of-scope positions are fully supported and defensible in an FTA review.
FAQ’s | VAT & Indirect Tax Consulting for JAFZA Companies
1. Our JAFZA company trades goods within the free zone. Is that subject to VAT?
It depends on the Designated Zone rules. Under the Designated Zone VAT framework, certain supplies of goods within a designated zone or between designated zones are treated as outside the scope of UAE VAT, provided specific conditions around the movement and use of the goods are met. The conditions are precise, and misapplying the treatment is a common, costly error, so we assess each of your goods transactions against them to ensure the correct treatment is applied and your position is defensible.
2. We supply goods from JAFZA to mainland UAE customers. How does VAT work?
A supply of goods from a JAFZA company to a mainland customer is generally treated as an import into the mainland, with specific VAT consequences including who accounts for the import VAT. Free zone to mainland supply VAT ensures these transactions are treated correctly and the import VAT position is properly established, so both you as the supplier and your mainland customer meet your obligations and the supply chain stays compliant.
3. Does the Designated Zone treatment apply to our services too?
No. The Designated Zone treatment applies to supplies of goods, not generally to services, which follow the normal UAE VAT rules. This is an important distinction, and treating services as out of scope because your company sits in a designated zone is a common error. We ensure the distinction is drawn correctly, so your services are treated properly under the standard rules while your qualifying goods transactions receive the designated zone treatment.
4. We buy services from overseas suppliers. How is VAT handled?
Under the reverse charge mechanism, your JAFZA company accounts for both the output and input VAT on the overseas service in the same return. For a fully taxable business this is usually VAT-neutral, but it must be recorded correctly, and failing to apply the reverse charge is a common error. We ensure every overseas service purchase is accounted for properly in your returns.
5. We import, export, and re-export goods through JAFZA. How is each treated for VAT?
Import export and re-export VAT treats each flow according to its nature, import VAT applies to goods entering the mainland, exports outside the UAE can be zero-rated where conditions are met, and re-exported goods that pass through without entering the mainland market have their own specific treatment. We ensure each flow is treated correctly and documented properly, so your trade VAT is accurate and your zero-rating and out-of-scope positions are fully supported in any FTA review.
Expert VAT Consulting for Your JAFZA Company
JAFZA companies operate under a VAT framework shaped by Designated Zone status and complex international trade, one of the most technically demanding VAT environments in the UAE. Our expert VAT & Indirect Tax Consulting for JAFZA Companies ensures every element, the Designated Zone framework, free zone to mainland supplies, complex supply chains, reverse charge, and import, export, and re-export VAT, is handled correctly, so your VAT position is always accurate, defensible, and efficient.
Our VAT and indirect tax consulting services and audit and assurance services help businesses build better reporting, compliance, and financial control, and you can explore the wider range of accounting services we offer across Dubai. Contact us today for a free VAT consultation, and for Legal Contract Drafting contact Omam Consultancy in Dubai.