Dubai Investment Park 2 (DIP 2) is one of the emirate’s major industrial and logistics zones, a large, established district built around manufacturing plants, warehousing and distribution facilities, and the industrial businesses that supply the wider UAE market and beyond.
For these businesses, VAT runs through the entire production and distribution cycle, import VAT on raw materials and equipment, output VAT on domestic sales, zero-rated exports, and the VAT considerations that come with holding and moving large volumes of stock. Expert VAT & Indirect Tax Consulting in DIP 2 keeps every one of these flows correctly managed.
Our VAT and indirect tax consulting service for DIP 2 businesses provides the manufacturing-aware and logistics-aware expertise that the zone’s producers and distributors need, ensuring every supply is correctly classified, all recoverable input tax is claimed, and every FTA obligation is met accurately and on time.
VAT for DIP 2’s Industrial Community
DIP 2’s manufacturers and distributors encounter UAE VAT across the full production and distribution cycle, each stage with its own treatment.
Manufacturers: Production businesses face import VAT on raw materials and equipment, output VAT on domestic sales, and export zero-rating on goods sold abroad, creating the full manufacturing VAT cycle.
Warehousing and logistics operators: Storage, distribution, and logistics services carry their own VAT treatment, and businesses holding goods on behalf of others have specific considerations.
Importers: Businesses importing raw materials, components, and finished goods face import VAT, which is generally recoverable as input tax where the goods are used in making taxable supplies.
Exporters: Manufacturers and distributors exporting goods outside the UAE may zero-rate those sales, provided the export conditions are met and documentation is retained.
Our VAT and Indirect Tax Services for DIP 2
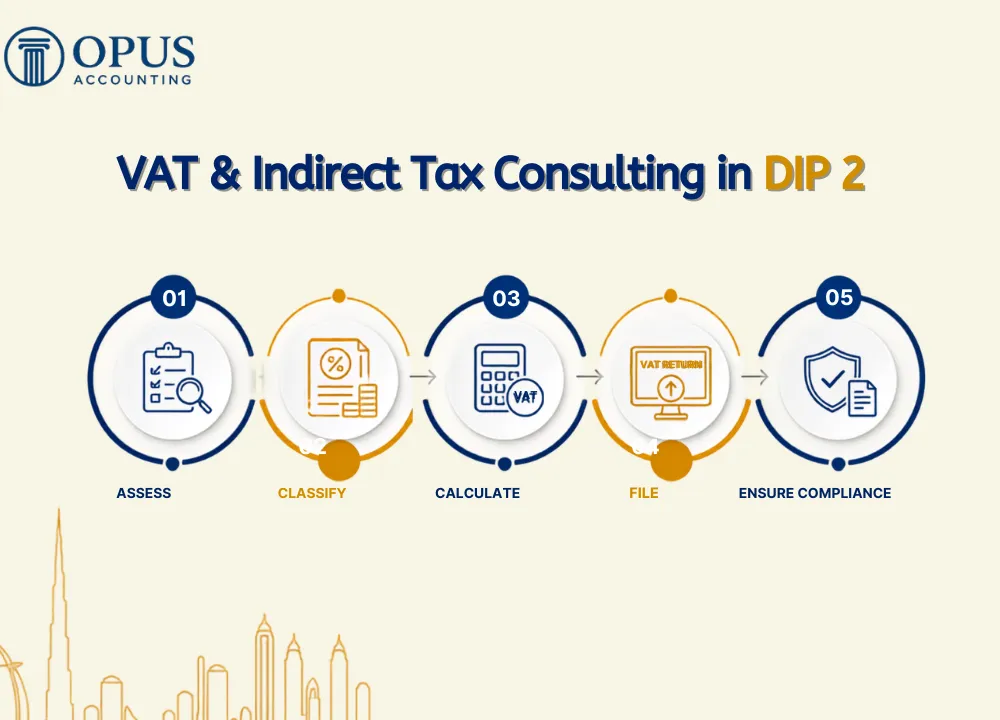
We provide a comprehensive VAT & Indirect Tax Consulting in DIP 2 service:
- Manufacturing VAT compliance across the production cycle.
- Warehousing and logistics VAT treatment.
- Import VAT recovery and documentation.
- Export zero-rating compliance and documentation.
- Industrial business VAT advisory.
- Input tax recovery review and optimisation.
- VAT registration, deregistration, and compliance management.
- Quarterly VAT return preparation and FTA portal submission.
- FTA voluntary disclosure and audit support.
- VAT health checks and compliance reviews.
Manufacturing and Industrial VAT Compliance
For DIP 2’s manufacturers, VAT runs through every stage of the production cycle, and managing it correctly protects both compliance and margin.
Manufacturing VAT compliance: A manufacturing business faces VAT at multiple points, import VAT on raw materials and capital equipment, recoverable input tax on production costs and overheads, output VAT on domestic sales, and zero-rating on exports. Manufacturing VAT compliance brings all of these together into a correct, coherent VAT position, ensuring output VAT is charged correctly on domestic sales, input tax on materials, equipment, and production costs is fully recovered, and the overall return accurately reflects the production cycle. For a DIP 2 manufacturer, getting this right protects both compliance and the cash flow that input recovery supports.
Industrial business VAT: Beyond the core production cycle, industrial businesses in DIP 2 face VAT on capital investment, equipment purchases, plant, and facility fit-out, all of which generate recoverable input tax, as well as on their ongoing operational costs. Industrial business VAT ensures the significant input tax that industrial operations generate is identified and recovered in full, which for capital-intensive businesses can be substantial, while output VAT on all taxable supplies is accounted for correctly.
Import VAT recovery: Manufacturers and industrial businesses import substantial volumes of raw materials, components, and equipment, and the import VAT on these is generally recoverable as input tax where the goods are used in making taxable supplies. Import VAT recovery ensures the import VAT your business incurs is correctly accounted for and recovered within your returns, using the correct documentation, so imported inputs remain broadly VAT-neutral and your working capital is protected.
Warehousing, Logistics, and Export VAT
Beyond manufacturing, DIP 2’s warehousing and distribution businesses and its exporters face specific VAT treatments across storage, logistics, and export.
Warehousing and logistics VAT: Storage, warehousing, and distribution services carry their own VAT treatment, generally standard-rated at 5 percent for domestic services, and businesses that hold or handle goods on behalf of others have specific considerations around how those services are charged and accounted for. Warehousing and logistics VAT ensures your storage and distribution services are classified and accounted for correctly, with domestic services standard-rated and any qualifying international elements treated appropriately, so your output VAT is accurate across your full service range.
Export zero-rating: Goods exported outside the UAE can be zero-rated, meaning no output VAT is charged, but only where the export conditions are met and the correct supporting evidence, customs documentation and proof of export, is retained. Export zero-rating is a frequent focus of FTA scrutiny, because missing evidence can turn a zero-rated sale into a standard-rated liability, and we put a robust documentation trail in place for every export so it is properly supported and defensible.
Input tax recovery: Across manufacturing, warehousing, and export activity, DIP 2 businesses accumulate substantial recoverable input tax, and our input tax recovery review works through your purchases and imports to confirm every recoverable amount is claimed and correctly documented, while excluding blocked items, directly improving your net VAT position and protecting cash flow.
FAQ’s | VAT & Indirect Tax Consulting in DIP 2
1. Our DIP 2 factory imports raw materials and sells both locally and for export. How does VAT work across all that?
Manufacturing VAT compliance brings your whole cycle together. Import VAT on raw materials is recoverable as input tax, output VAT at 5 percent applies to your domestic sales, and your exports can be zero-rated where the conditions are met. We ensure each stage is treated correctly so your return accurately reflects the full production cycle, your input tax is fully recovered, and your cash flow is protected.
2. We import a lot of raw materials and equipment. Can we recover the import VAT?
Yes. Import VAT recovery ensures the import VAT on your raw materials, components, and equipment is correctly accounted for and recovered within your VAT returns, using the correct documentation, provided the goods are used in making taxable supplies. This keeps your imported inputs broadly VAT-neutral and protects the working capital that would otherwise be tied up, which matters for a capital-intensive manufacturing business.
3. We provide warehousing and distribution services in DIP 2. How is VAT applied?
Warehousing and logistics VAT treats domestic storage and distribution services as standard-rated at 5 percent, with specific considerations where you hold or handle goods on behalf of others, and any qualifying international elements treated appropriately. We ensure your storage and distribution services are classified and accounted for correctly, so your output VAT is accurate across your full range of services.
4. We export goods from DIP 2. How do we make sure our zero-rating is safe?
Export zero-rating applies where goods physically leave the UAE and the export conditions are met, but only if you retain the correct evidence, customs documentation and proof of export. Because this is a frequent focus of FTA scrutiny, we put a robust documentation trail in place for every export, so your zero-rating is properly supported and cannot be reclassified as a standard-rated liability for want of evidence.
5. How do we make sure we recover all the input VAT our operation generates?
Our input tax recovery review examines all your purchases and imports, raw materials, equipment, plant, fit-out, and overheads, to confirm every recoverable amount is claimed and correctly documented, while excluding blocked items. Industrial and manufacturing operations generate substantial recoverable input tax, and many businesses under-recover through incomplete records, so tightening this directly improves your net VAT position and cash flow.
Expert VAT Consulting for Your DIP 2 Business
DIP 2’s manufacturers, warehousing operators, and distributors run VAT-intensive operations spanning imports, production, storage, domestic sales, and exports. Our expert VAT & Indirect Tax Consulting in DIP 2 service ensures every one of these is handled correctly and efficiently, from manufacturing and industrial VAT to import recovery, warehousing VAT, and export zero-rating, so your VAT position is always accurate, defensible, and cash-flow efficient.
Our VAT and indirect tax consulting services and audit and assurance services help businesses build better reporting, compliance, and financial control, and you can explore the wider range of accounting services we offer across Dubai. Contact us today for a free VAT consultation, and for Legal Contract Drafting contact Omam Consultancy in Dubai.