Al Garhoud is a strategically positioned Dubai community next to Dubai International Airport, a neighbourhood whose commercial sector spans logistics businesses, hospitality enterprises, professional service firms, and healthcare providers.
Each of these sectors carries distinct considerations under the UAE CT framework, which is exactly why corporate tax filing services for Al Garhoud businesses cannot be applied as a single template. What a freight forwarder needs from income recognition and expense deductibility looks nothing like what a hotel or a clinic needs.
Our corporate tax filing services for Al Garhoud businesses provides that sector-specific CT expertise, ensuring accurate taxable income calculation for every business type in the community, complete compliance with the Federal Tax Authority, and effective CT planning that fits your industry rather than a generic checklist.
Corporate Tax Across Al Garhoud’s Business Sectors
Al Garhoud businesses face distinct CT considerations based on their sector:
Logistics and freight businesses: Freight forwarders and logistics operators recognise revenue from service completion, typically when goods are delivered or customs clearance is provided. Complex supply chain transactions, multi-currency invoicing, and significant related party arrangements are common CT issues here.
Hospitality businesses: Hotels and restaurants recognise revenue from accommodation bookings, food and beverage service, and events. Advance bookings, deposits, and no-show charges each carry specific revenue recognition implications, and service charge collection and distribution has CT relevance too.
Healthcare and medical practices: Clinics and dental practices calculate taxable income from clinical services after allowable medical practice costs, with specific considerations around insurance billing, practitioner compensation, and medical equipment depreciation.
Professional service firms: Consulting and advisory businesses calculate taxable income from professional fees after deductible operating expenses, with revenue recognition timing particularly relevant for longer-term engagements.
Our Corporate Tax Filing Services for Al Garhoud
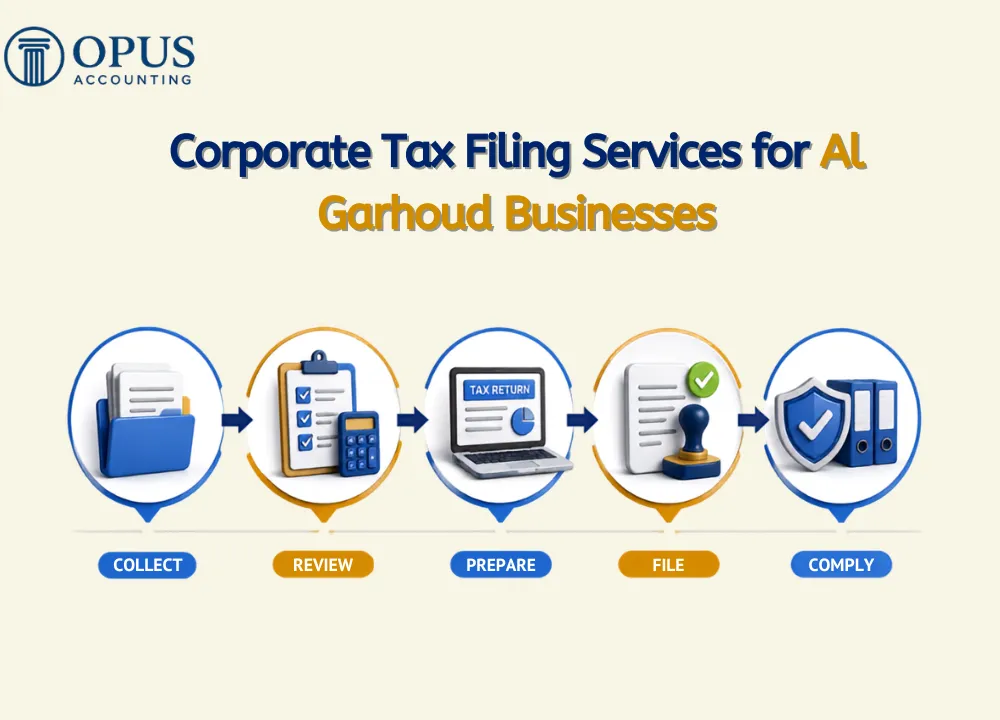
We provide a comprehensive corporate tax filing service for Al Garhoud businesses:
- FTA corporate tax registration for all business types
- Small Business Relief assessment and election
- Logistics and freight business taxable income calculation
- Hospitality revenue recognition and CT treatment
- Healthcare practice CT analysis
- Expense deductibility review across all sectors
- Related party transaction analysis
- Annual CT return preparation and FTA submission
- CT payment scheduling
- FTA correspondence support
- Sector-specific CT planning advisory
For most community businesses, the Small Business Relief assessment is the first thing worth getting right, because it determines whether tax is payable at all. We handle that assessment alongside the full corporate tax filing for Al Garhoud businesses, so eligibility and compliance are managed together rather than in isolation.
Logistics and Freight Business CT Compliance
Al Garhoud’s logistics sector, positioned next to Dubai International Airport, includes businesses with specific CT compliance characteristics:
Revenue recognition for freight services: Revenue from freight forwarding engagements is recognised when the service obligation is satisfied, typically at delivery. For multi-leg freight arrangements, the timing of revenue recognition may need careful analysis under IFRS 15.
Customs duty as pass-through: When a freight forwarder pays customs duties on behalf of clients and is reimbursed, the duty reimbursement is typically a pass-through item rather than revenue, provided the forwarder acts as agent. The gross versus net presentation of such items affects reported revenue and therefore the Small Business Relief threshold assessment.
Foreign currency transactions: Logistics businesses often invoice in USD or EUR while incurring costs in multiple currencies. Foreign exchange gains on open transactions must be included in taxable income, and exchange losses are deductible.
Agent versus principal arrangements: The classification of a logistics business as agent (acting on behalf of a customer) or principal (taking ownership of the service) decides whether gross revenue or net margin is recognised. This logistics revenue recognition question, agent versus principal, has direct implications for reported revenue levels and CT liability, and it feeds straight into your financial reporting as well.
Hospitality Business CT Compliance
Hotels and restaurant businesses in Al Garhoud face specific CT compliance issues:
Advance booking revenue: Room booking deposits and event reservation deposits received in advance of the stay or event create deferred income, only taxable in the period when the accommodation or service is delivered.
No-show and cancellation income: Income from no-show fees and non-refundable cancellation charges is recognised when the right to the payment is established, typically when the cancellation or no-show occurs.
Service charge CT treatment: Service charges collected from customers and distributed to staff are not income of the business; they pass through the business to eligible employees. The service charge mechanism should be reflected correctly in the financial statements so these inflows are not incorrectly included in the business’s taxable income.
Food and beverage cost deductibility: F&B cost of goods (ingredients, beverages, and consumables) is fully deductible as a trading expense. However, F&B expenses with a personal or entertainment element may fall under the 50% entertainment expense limitation.
FAQ’s | Corporate Tax Filing Services for Al Garhoud Businesses
1. We are an Al Garhoud freight forwarder. We pay customs duties on behalf of clients and get reimbursed. Is the reimbursement our revenue?
If you act as an agent, paying duties on behalf of clients without taking ownership risk, the duty reimbursement is a pass-through and not your revenue. Only your service fee counts as revenue. Getting this logistics revenue recognition question right (agent versus principal) matters for your Small Business Relief threshold assessment and an accurate CT return.
2. Our Al Garhoud hotel receives non-refundable deposits for event bookings. When are these taxable?
Non-refundable deposits become taxable income when the right to retain them is established. That may be at the time of booking, if the deposit is earned unconditionally, or at the event date, if it is earned as the service is delivered. We analyse your specific booking terms and apply the correct recognition timing.
3. We are an Al Garhoud medical clinic with revenues of AED 2.5 million. Do we qualify for Small Business Relief?
Yes. At AED 2.5 million in revenue you are eligible for Small Business Relief. Our Small Business Relief assessment confirms your full eligibility, manages the registration and filing process, and elects the relief in your annual CT return. No tax is payable, but the compliance obligations still apply.
4. Our logistics business has significant related party transactions with our parent company. Is this a transfer pricing issue?
Yes. Any transaction between related parties, including with a parent company, is subject to transfer pricing rules, and the pricing must be at arm’s length. Our related party transaction analysis reviews all such arrangements and prepares the documentation needed to demonstrate compliance.
5. Our Al Garhoud restaurant covers client meals and staff hospitality. Are these fully deductible?
Not always. Straight food and beverage cost of goods is fully deductible as a trading expense, but costs with a personal or entertainment element can fall under the 50% entertainment expense limitation. We review your expense categories so the deductible and restricted portions are split correctly on your corporate tax filing.
Expert Corporate Tax Filing for Your Al Garhoud Business
Al Garhoud businesses operate in one of Dubai’s most commercially connected communities. Our expert corporate tax filing service ensures your CT obligations are managed with the sector-specific expertise your business deserves. Contact us today for a free consultation.