Dubai Industrial City is one of the UAE’s largest and most strategically significant industrial free zones, a purpose-built manufacturing hub where food producers, chemical manufacturers, building material businesses, and machinery companies generate significant economic value within a free zone framework that creates specific UAE Corporate Tax opportunities and obligations.
DIC companies may access the Qualifying Free Zone Person regime’s 0% rate on qualifying income, but the conditions are demanding and the analysis requires specialist expertise. That is why corporate tax filing services for Dubai Industrial City businesses must combine deep manufacturing knowledge with precise CT compliance capability.
Our corporate tax filing service for Dubai Industrial City businesses provides the definitive QFZP eligibility assessment for manufacturers, comprehensive manufacturing CT compliance, and expert transfer pricing documentation that industrial free zone businesses need to navigate the UAE CT framework correctly.
Corporate Tax for Dubai Industrial City Companies
DIC companies face UAE CT within the DIC free zone framework:
QFZP eligibility for DIC manufacturers: DIC manufacturing companies may be eligible for QFZP status, subject to adequate substance in the UAE, qualifying income conditions, and the de minimis threshold. A thorough QFZP eligibility assessment for manufacturers determines whether your primary output qualifies based on its destination and activity classification. For manufacturers whose production is sold overseas or to other free zone entities, QFZP eligibility may be achievable.
De minimis threshold management: Revenue from UAE mainland customers is generally non-qualifying income for QFZP purposes. If UAE domestic sales represent more than 5% of total revenue (or AED 5 million), QFZP status cannot be maintained and standard CT applies. Our corporate tax filing services for Dubai Industrial City businesses include ongoing monitoring of this threshold to prevent unintended disqualification.
Manufacturing substance: DIC manufacturers must demonstrate adequate substance, including employees engaged in production activities, manufacturing equipment and facilities within the zone, and adequate operating expenditure. The substance requirement is proportionate to the scale and nature of manufacturing activities.
Audited financial statement coordination: QFZP status requires audited financial statements. For DIC manufacturers not currently subject to statutory audit, establishing an audit process is a necessary precondition for QFZP compliance. Our audited financial statement coordination service connects you with qualified auditors and ensures your statements meet FTA{target=”_blank”} requirements.
Our Corporate Tax Filing Services for Dubai Industrial City
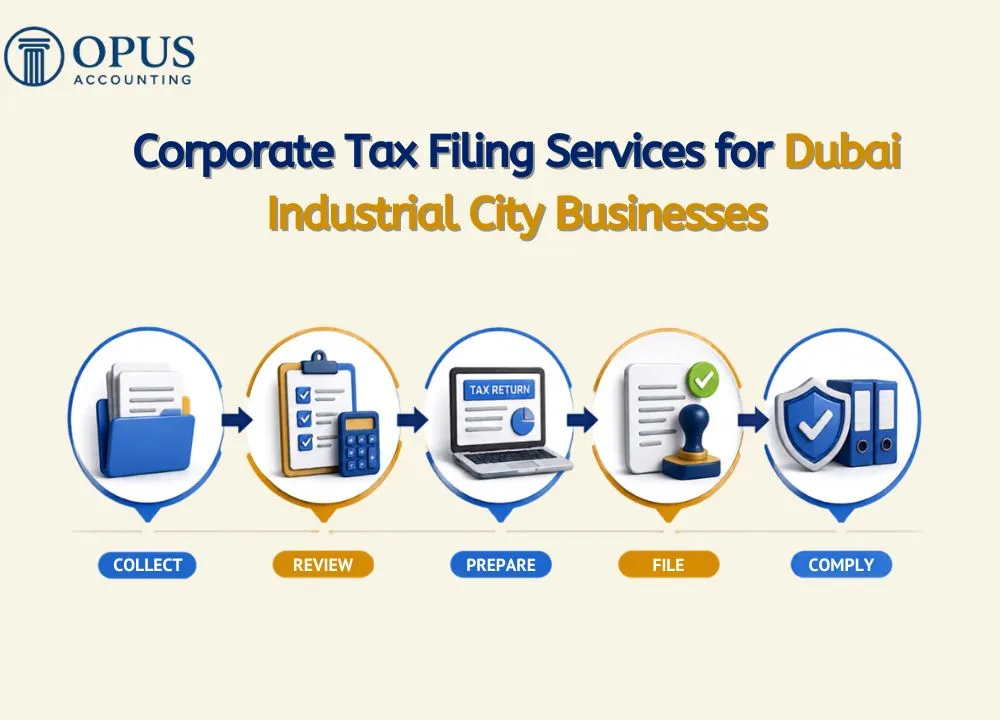
We provide comprehensive corporate tax filing services for Dubai Industrial City businesses across every manufacturing and industrial category:
- QFZP eligibility assessment for manufacturers, covering substance, qualifying income, and threshold analysis
- Manufacturing revenue qualifying income classification
- UAE domestic versus export sales analysis
- Substance documentation for DIC QFZP entities
- Audited financial statement coordination with approved audit firms
- Manufacturing cost accounting and taxable income calculation
- Transfer pricing documentation for intercompany supply arrangements
- FTA{target=”_blank”} corporate tax registration
- Annual CT return reflecting correct DIC CT treatment
- Advance CT payment management
- Master File and Local File preparation for qualifying entities
- FTA audit support
QFZP Analysis for DIC Manufacturers
For manufacturing businesses in Dubai Industrial City, the QFZP qualifying income analysis focuses on the destination of manufactured goods:
Export revenue: Revenue from manufactured goods exported to overseas buyers is generally qualifying income for QFZP purposes, provided the manufacturing activities are conducted within the DIC free zone and the goods meet the relevant qualifying activity criteria. Corporate tax filing services for Dubai Industrial City businesses must classify this revenue accurately for each product line.
Sales to other UAE free zone companies: Revenue from sales to other QFZP entities within UAE free zones may qualify as qualifying income, subject to the specific goods and activity classifications.
Sales to UAE mainland customers: Revenue from sales to UAE mainland companies or consumers is generally non-qualifying income. For manufacturers with significant domestic UAE sales, managing the proportion of non-qualifying revenue against the de minimis threshold is critical to maintaining QFZP status.
Manufacturing services income: Revenue from toll manufacturing services, where a DIC company processes raw materials owned by clients, may have different qualifying income characteristics from revenue from the sale of finished goods. Our QFZP eligibility assessment for manufacturers evaluates the qualifying status of each revenue type for your specific manufacturing model, ensuring your CT return reflects the correct treatment.
Transfer Pricing for DIC Manufacturing Groups
Most DIC manufacturers are part of larger corporate groups with international supply chain relationships. These intercompany arrangements require specific transfer pricing documentation:
Raw material purchase pricing: If a DIC manufacturer purchases raw materials from a related overseas supplier, the purchase price must be at arm’s length. An inflated related party purchase price reduces UAE taxable income, which the FTA will examine in detail. Our transfer pricing documentation service ensures your intercompany purchase arrangements are fully defensible.
Finished goods transfer pricing: For DIC manufacturers that sell their output to a related distribution company, whether in the UAE or overseas, the transfer price must reflect an appropriate profit margin for the manufacturing entity. The FTA expects the manufacturing entity to earn a return commensurate with its functions, assets, and risks. Manufacturing cost accounting and taxable income calculation is essential here, as it determines the cost base from which an appropriate manufacturing margin is derived.
Group financing and 30% EBITDA interest limitation: Intercompany loans from a group treasury company must carry arm’s length interest rates. For DIC manufacturers with significant capital requirements financed through intercompany debt, both the interest rate and the group financing and 30% EBITDA interest limitation require careful management. Exceeding the 30% EBITDA cap means excess interest is non-deductible, directly increasing your CT liability.
Master File and Local File: DIC manufacturers with significant related party transactions must prepare a transfer pricing Master File and Local File, the standard OECD documentation framework now applicable under UAE CT. Our corporate tax filing services for Dubai Industrial City businesses include full Master File and Local File preparation, ensuring your transfer pricing positions are documented to the standard the FTA expects.
FAQ’s | Corporate Tax Filing Services for Dubai Industrial City Businesses
1. What does a QFZP eligibility assessment for manufacturers involve?
A QFZP eligibility assessment for manufacturers involves analysing your revenue streams to classify qualifying versus non-qualifying income, reviewing your substance position (employees, assets, and expenditure within DIC), checking the de minimis threshold against your UAE domestic sales, and confirming whether your manufacturing activities meet the qualifying activity criteria. We provide a clear eligibility determination with supporting documentation.
2. What does manufacturing cost accounting and taxable income calculation involve for DIC businesses?
Manufacturing cost accounting and taxable income calculation involves building a complete cost model for your production operations, including raw materials, direct labour, manufacturing overheads, and depreciation. This cost base determines your gross manufacturing margin and, ultimately, your taxable income. Accurate cost accounting ensures you do not overpay CT due to incorrect cost classification.
3. Can you handle financial reporting alongside CT filing for our DIC business?
Yes. Many of our DIC clients combine corporate tax filing services for Dubai Industrial City businesses with our financial reporting and bookkeeping services for a fully integrated finance and compliance solution. Accurate financial reporting is the foundation for correct CT calculations.
4. How can we get started with corporate tax filing services for Dubai Industrial City businesses?
Simply contact us for a free consultation. We will review your current CT position, assess your QFZP eligibility, and recommend a tailored filing programme that ensures full compliance from the first return.
5. Our DIC company has not previously had audited financial statements. Can we still file a CT return?
Yes, you can file a CT return from IFRS-compliant management accounts. However, audited statements are required for QFZP status. Our audited financial statement coordination service connects you with approved auditors and manages the process so your first CT period audit is completed on time.
Expert Corporate Tax Filing for Your Dubai Industrial City Business
Dubai Industrial City manufacturers are building the UAE’s industrial future. Our expert corporate tax filing services for Dubai Industrial City businesses ensure the tax management of those manufacturing operations is as efficient and well-managed as the production lines themselves. For broader financial advisory support, our team can connect your CT strategy with long-term growth planning.
Contact us today for a free consultation. You can also explore our full range of services to see how we support industrial businesses across Dubai.
Our Compliance & Licensing Services help DIC businesses maintain their regulatory standing, and for Legal Contract Drafting contact Omam Consultancy in Dubai.